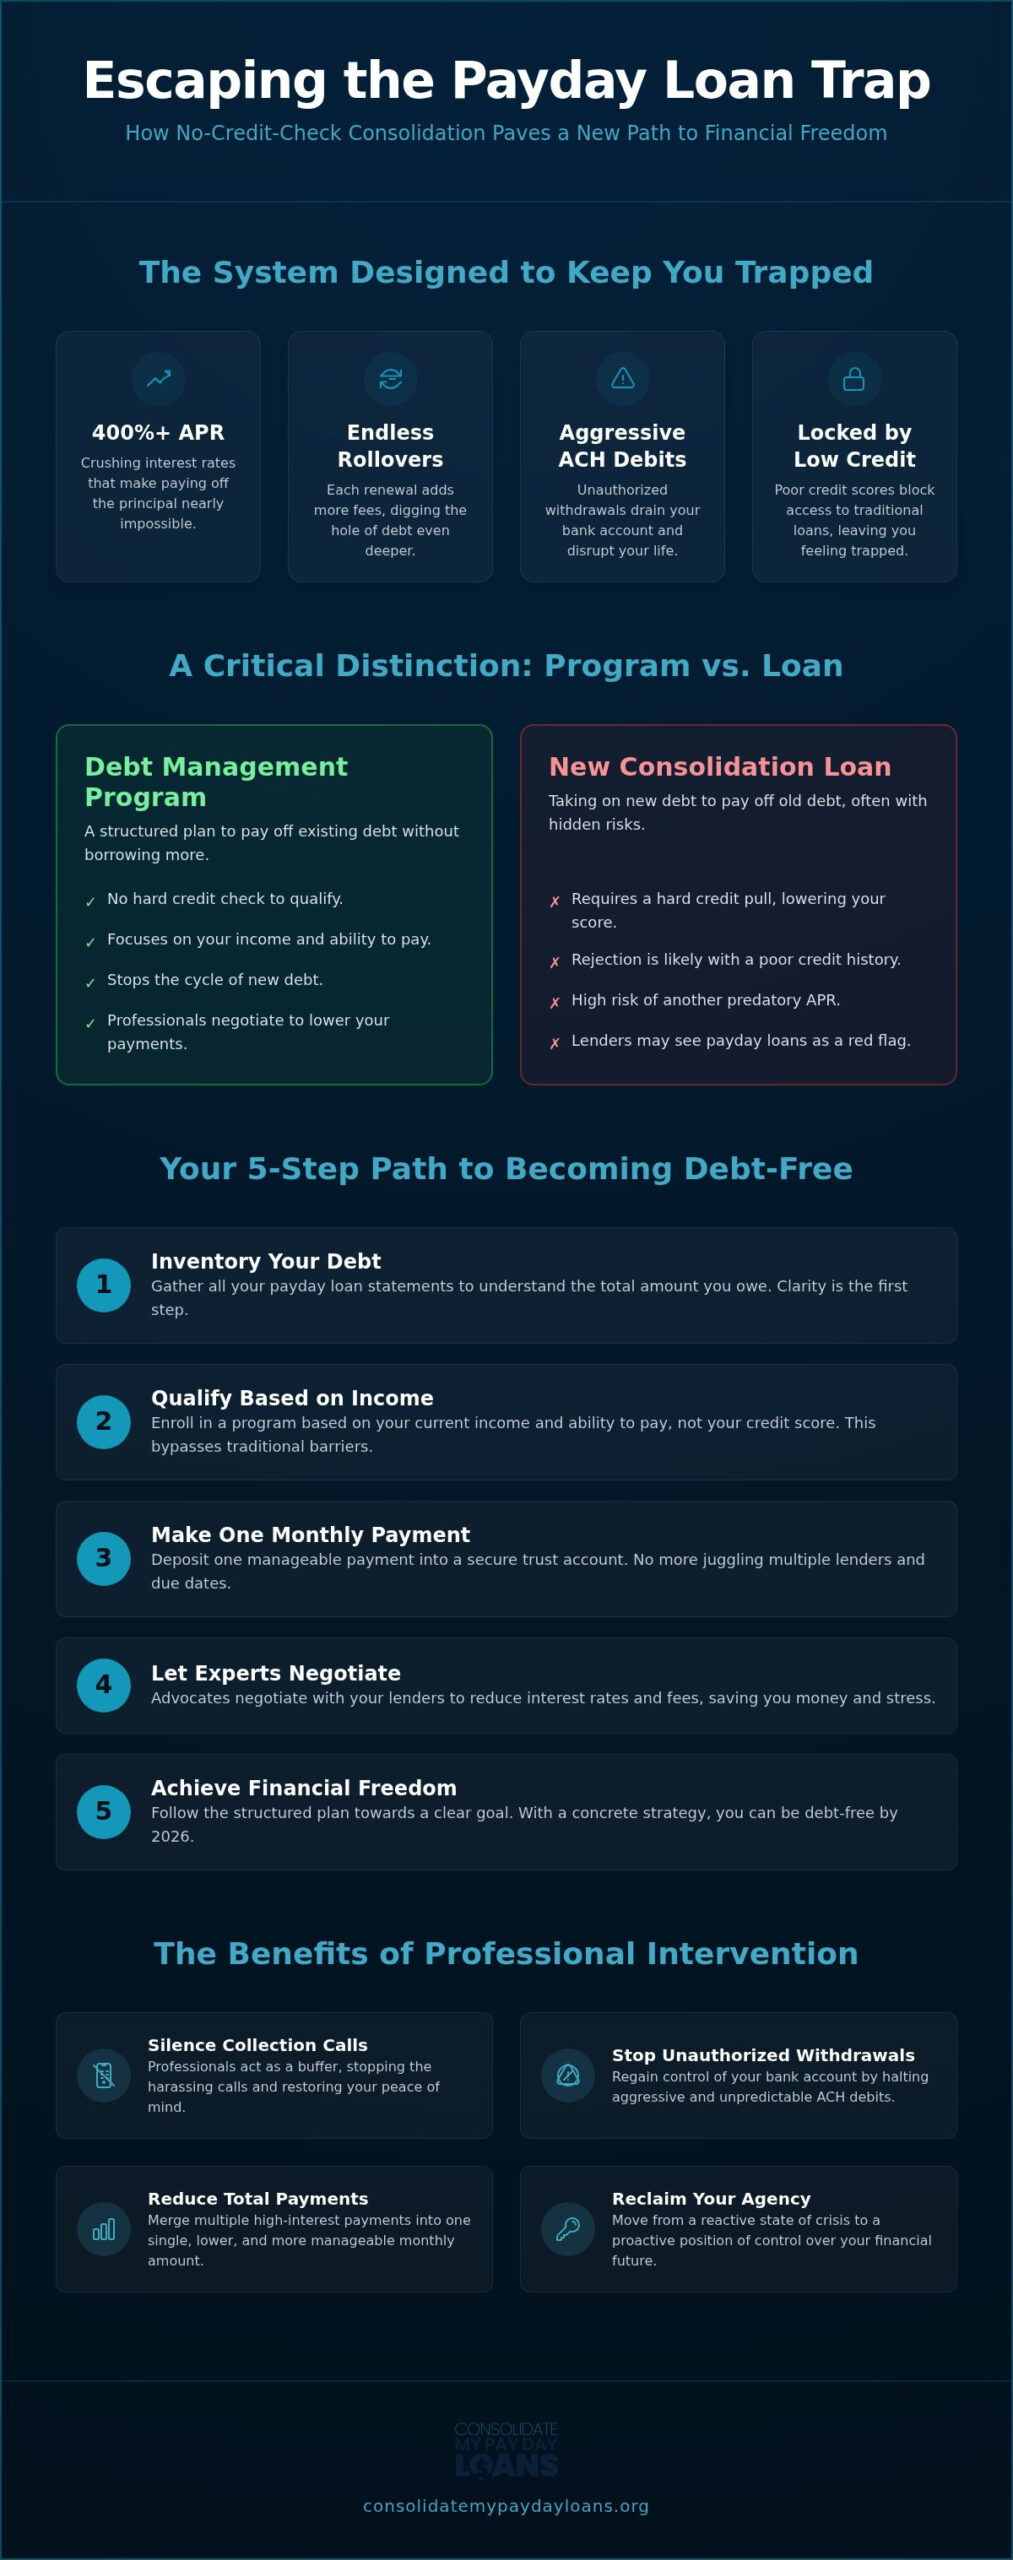
You aren’t just struggling with a loan; you’re fighting a system specifically designed to keep you in debt. With interest rates often soaring above 400% APR, a single payday loan can quickly mutate into an endless cycle of rollovers that drain your bank account through aggressive ACH withdrawals. It’s a heavy burden that leaves you feeling trapped, especially when constant collection calls interrupt your daily peace of mind. You likely feel that your credit score is a locked door standing between you and any real financial relief.
We understand that traditional bank loans aren’t an option when your credit has taken a hit. However, a low score doesn’t have to be a life sentence. This guide explores how specialized no credit check payday loan consolidation programs work to stop the cycle of debt by focusing on management and negotiation rather than new high-interest borrowing. You’ll discover how to halt the predatory lending cycle, reduce your total monthly payments, and finally silence the collection agents. We will walk through the mechanics of professional debt management and show you exactly how to achieve a clear path to being debt-free by 2026. It is time to stop the automatic withdrawals and reclaim your personal agency.
Key Takeaways
- Learn why no credit check payday loan consolidation functions as a debt management program rather than a new loan, allowing you to bypass traditional credit score barriers.
- Understand how these programs use your income and debt-to-income ratio to qualify you for relief, even if you have a history of lender rejections.
- Discover the negotiation techniques used to reduce interest rates and fees, effectively halting the cycle of costly loan rollovers.
- Access a structured 5-step plan to inventory your debt and use a specialized calculator to visualize your path toward financial recovery.
- Find out how professional intervention can stop aggressive collection calls and unauthorized bank withdrawals, restoring your peace of mind.
Understanding No Credit Check Payday Loan Consolidation Options
Many people assume that consolidating debt always requires taking out a new loan. However, no credit check payday loan consolidation is actually a structured management program designed to resolve debt without adding new high-interest obligations. It isn’t a new loan; it is a management plan. Traditional banks and credit unions typically reject payday loan borrowers because their debt-to-income ratios are too high or their credit scores have already been damaged by the cycle of rollovers. Unlike a standard personal loan application, which involves a hard credit pull that can further lower your score, program enrollment focuses on your current income and total debt. Your past financial struggles are the very reason these programs exist. They are the starting point for recovery, not a reason for rejection.
Why a New Loan Might Not Be the Answer
Taking out a new loan to pay off old ones often feels like the most logical step. The reality is often more complex. Borrowers with credit scores below 580 frequently find that the only lenders willing to help are just as predatory as the payday lenders themselves. These lenders often hide astronomical APRs in the fine print, which can exceed the 400% rates you’re already trying to escape. Debt management is a safer alternative because it doesn’t involve borrowing more money. It stops the cycle of new debt by focusing on paying down the principal you already have. By choosing a management path, you avoid the risk of a new lender checking your credit and seeing the payday loan history as a red flag. This helps preserve your credit score while you work on an exit strategy.
The Role of Debt Relief in Consolidation
Understanding Debt Consolidation is essential for anyone feeling overwhelmed by multiple due dates and aggressive collection calls. In a professional relief program, consolidation means merging your monthly payments rather than just merging your balances into a new principal. Expert advocates step in to negotiate directly with your lenders on your behalf. They use insider knowledge of the industry to secure lower fees and reduced interest rates that you likely couldn’t get on your own. This specialized no credit check payday loan consolidation method prioritizes your stability over a FICO score. This professional intervention creates a buffer between you and the lenders. Beyond the math, there’s a profound psychological relief in knowing that a professional team is handling the logistics. You can stop worrying about which loan to pay first and start focusing on your path to financial recovery. Having a single, managed payment simplifies your life and restores your sense of agency over your future.
How Debt Management Programs Bypass Credit Requirements
Traditional lenders rely heavily on FICO scores because they view your past as a predictor of your future. This approach often leaves borrowers in a lurch when they need help the most. Professional no credit check payday loan consolidation works differently by prioritizing your current income and your debt-to-income ratio. Instead of a hard credit pull that penalizes you for seeking help, these programs evaluate your ability to maintain a consistent payment plan. This shift in focus allows individuals with poor credit to qualify for relief based on their actual cash flow rather than a three digit number. It is a system built for recovery, specifically tailored for unsecured payday debt that often carries interest rates near 400%.
The cornerstone of this process is the use of a dedicated trust account. Rather than sending multiple payments to various lenders, you make one monthly deposit into this secure account. As funds accumulate, professional advocates use those resources to satisfy the negotiated settlements with your creditors. This structure ensures that your money is working toward a specific goal: eliminating the principal balance. If you are feeling overwhelmed by the math, you can explore professional relief options to see how this single payment model fits your budget.
Negotiating with Predatory Lenders
Lenders often settle for less than the full balance because they know that 80% of payday loans are eventually rolled over, according to industry research. They would rather receive a guaranteed portion of the debt than risk getting nothing if a borrower is forced into a total default. Professional consolidation services carry significant leverage that individual borrowers lack. They understand the “insider” collection cycles and know exactly when a lender is most likely to agree to a reduction in interest and fees. If a lender refuses to cooperate initially, your advocate continues to apply pressure, often leading to a more favorable outcome as the lender realizes you have professional representation.
Regaining Control of Your Bank Account
One of the most stressful aspects of the payday loan trap is the constant fear of unauthorized bank withdrawals. What is a Payday Loan? At its core, it is a high-cost debt that often relies on direct access to your checking account. Stopping these automatic ACH withdrawals is essential to prevent cascading overdraft fees and ensure your paycheck stays where it belongs. Programs guide you through the process of notifying both the lender and your bank that you are withdrawing your consent for these transactions. ACH revocation is a consumer right under the Electronic Fund Transfer Act. By reclaiming this control, you stop the bleeding and can finally manage your daily expenses with confidence.
Comparing Consolidation Loans vs. Relief Programs
Choosing between a new loan and a management program is a pivotal decision for anyone stuck in the payday loan trap. Traditional lenders often promote personal loans as the primary tool to Consolidate Bills Into One Monthly Payment. However, the eligibility requirements for these loans are strict. Most reputable lenders require a credit score of at least 600 and a stable debt-to-income ratio. If you meet these criteria, a loan can provide an immediate payoff of your high-interest debt. For those with credit scores below 580, the reality is different. At the end of 2025, the average APR for a debt consolidation loan for borrowers with poor credit was 30.02%. While this is lower than 400%, it still adds to your total debt burden through origination fees that range from 1% to 10%.
A no credit check payday loan consolidation program offers a different path by prioritizing your current budget over your past credit mistakes. Instead of waiting days for a loan approval that might never come, relief programs provide nearly immediate payment reduction. You stop paying the predatory interest rates and start making a single, affordable payment into a managed account. This shift focuses on eliminating the debt entirely through negotiation rather than just moving the balance to a new lender. While a new loan might offer a slight boost to your credit score by lowering your utilization, the hard credit pull required for the application can cause an immediate dip. Relief programs focus on the long term goal of being debt-free, which is the most sustainable way to rebuild your financial standing.
When a Consolidation Loan Makes Sense
If your credit score sits in the “fair” range of 600 or higher, a consolidation loan might be a viable exit strategy. The main benefit is the ability to wipe out multiple payday balances in a single day, effectively resetting your financial clock. This is particularly effective if you can secure an APR below 20%. For individuals who are also juggling high-interest revolving debt, you might consider Credit Card and Payday Loan Consolidation: A Unified Exit Strategy for 2026. This approach works best when you have the discipline to avoid taking out new loans once the old ones are paid off.
Why Relief Programs Win for Bad Credit
Relief programs are specifically designed to eliminate the “credit-shaming” that often occurs at traditional banks. Enrollment is based on what you can actually afford to pay each month, not a number generated by a credit bureau. These programs provide a protective buffer between you and the lenders, halting the aggressive collection calls that fuel daily stress. By focusing on affordability and negotiation, you gain a partner who is tough on the systemic problem but compassionate toward your individual situation. It’s a methodical way to regain your agency without the fear of another rejection letter.
Your 5-Step Plan to Consolidate Payday Loans with Poor Credit
Escaping the debt cycle requires a methodical strategy. When your credit score is low, you need a path that prioritizes your current income over your past financial history. This 5-step plan provides a structured methodology to regain control. Follow these actions to transition from constant stress to financial stability.
- Step 1: Inventory your loans. List every lender, total balance, interest rate, and upcoming due date. This inventory is your roadmap to freedom. Without a clear picture of your total obligations, you cannot build an effective defense.
- Step 2: Use the right tools. Before making any decisions, use a payday loan consolidation calculator to see your potential savings. Visualizing the difference between your current payments and a managed plan builds the momentum you need to continue.
- Step 3: Revoke ACH authorizations. Stop the immediate drain on your finances by notifying your bank and lenders that you’re withdrawing consent for automatic withdrawals. This keeps your paycheck in your account where it belongs.
- Step 4: Enroll in a specialized program. Choose a no credit check payday loan consolidation program that manages all lender communication on your behalf. This step replaces multiple high-interest debts with a single, manageable payment.
- Step 5: Stay committed. Commit to your new monthly payment and strictly avoid taking out any new “quick cash” loans. Breaking the cycle requires a firm stance against the lending practices that caused the initial turbulence.
Stopping the Bleeding: The First 48 Hours
The first two days after realizing you cannot make a rollover are the most critical. You must take immediate action to stop the financial bleeding. Contact your bank to explain that you are revoking authorization for specific predatory withdrawals. This prevents cascading overdraft fees that often follow a missed payday payment. Document every interaction with your lenders, including the time of calls and the names of representatives. This paper trail is essential if you face aggressive collection tactics or harassment. If you’re feeling overwhelmed by these initial steps, you can start your payday loan relief journey with professional support today.
Long-Term Financial Recovery
Recovery is a marathon, not a sprint. Once you’ve enrolled in no credit check payday loan consolidation, your focus shifts to long-term stability. Build a basic budget that prioritizes your single consolidation payment above all other non-essential spending. You will likely receive new “quick cash” offers during your recovery period. These are traps designed to pull you back into the cycle. Ignore them. As you successfully complete your management plan, you’ll naturally transition from debt relief to active credit building. Reclaiming your agency over your financial life is the ultimate reward for your persistence.
Why Consolidate My Payday Loans is Your Best Exit Strategy
Choosing the right partner for your recovery is just as important as the decision to seek help. Consolidate My Payday Loans, operated by Solid Ground Financial since 2004, brings over two decades of specialized experience to your corner. We don’t operate as a generic lending marketplace with hundreds of unrelated products. Instead, we focus exclusively on the mechanics of payday loan relief. This singular focus gives us a distinct advantage when dealing with lenders who rely on aggressive tactics to keep you in the rollover cycle. Our all-in-one service handles every aspect of the process, from the initial negotiation of interest and fees to the management of your single monthly payment. By choosing a dedicated no credit check payday loan consolidation path, you gain a protective advocate committed to your long-term stability.
Expertise That Makes a Difference
Our team understands the specific pressures you face. We use insider knowledge of the lending industry to counter the high-pressure collection strategies that often lead to financial paralysis. Utilizing a specialized payday loan hardship program allows us to restructure your obligations into something that fits your actual budget. We prioritize your psychological peace and financial health over the profits of predatory lenders. This isn’t just about the numbers; it’s about reclaiming your personal agency. We’ve seen every tactic in the book and we know exactly how to protect our clients from further financial harm.
Starting Your Journey Today
Starting your journey is a straightforward, transparent process. During your initial consultation, our specialists will review your loan inventory and discuss your specific financial goals. There are no hidden fees or complex jargon. We provide a clear breakdown of how the program works and what you can expect at every stage of your recovery. When you enroll in no credit check payday loan consolidation, you aren’t just signing up for a service; you’re gaining a partner in your recovery. You don’t have to face the overwhelming weight of this debt cycle alone. Our role is to act as a stable anchor while you navigate toward a debt-free future. If you’re ready to stop the automatic withdrawals and silence the collection calls, contact us today for a free debt assessment.
Reclaiming Your Financial Agency in 2026
Breaking the cycle of high-interest debt requires a shift from borrowing to management. You’ve learned that no credit check payday loan consolidation isn’t about finding another lender; it’s about finding a protective advocate. By revoking ACH authorizations and following a structured repayment plan, you can finally stop the drain on your bank account. Our A+ rated strategies are designed to silence aggressive collection calls and reduce your total monthly payments through expert negotiation.
We bring over 20 years of debt management experience through Solid Ground Financial to every client we serve. You don’t have to navigate these complex financial traps by yourself. Use our specialized payday loan savings calculator to see exactly how much you can save. When you’re ready to start your journey toward psychological peace, Get Your Free Payday Loan Consolidation Quote Now. You have the power to change your financial future, and we’re here to provide the stable anchor you need.
Frequently Asked Questions
Can I really consolidate payday loans with no credit check?
Yes, you can consolidate your payday loans without a traditional credit check by enrolling in a no credit check payday loan consolidation program. Unlike a bank loan that requires a high FICO score, these programs qualify you based on your current income and total debt load. This approach ensures that your past financial difficulties aren’t a barrier to your recovery. It’s a structured path designed specifically for those who need relief but can’t access traditional credit.
Will consolidating my payday loans stop the collection calls?
Yes, professional intervention is designed to halt the constant cycle of aggressive collection calls. Once you are enrolled, your consolidation specialists take over all communication with your lenders. This professional buffer means you no longer have to deal with high-pressure tactics or harassment. Most lenders stop their direct outreach once they know you’ve engaged a management service. You can finally enjoy the psychological peace that comes with a quiet phone and a managed plan.
How much can I save by using a payday loan consolidation program?
Your total savings depend on the specific interest rates and fees your lenders are currently charging. By negotiating for reduced interest and the elimination of late fees, a management program can significantly lower your total payout over time. You should use a specialized calculator to estimate your specific savings based on your unique loan inventory. This tool helps you see the tangible benefit of moving from individual high-cost loans to a single, affordable monthly payment.
What happens if I already have a payday loan in collections?
Loans already in collections are still eligible for consolidation and relief. In many cases, third-party collection agencies are more willing to settle for a reduced amount than the original payday lender. Your consolidation team will work directly with these agencies to negotiate a fair resolution. This process helps you resolve old debts that are weighing down your financial future. It’s a proactive way to resolve your outstanding balances without facing the threat of legal action.
Is payday loan consolidation better than filing for bankruptcy?
Consolidation is often a preferred alternative to bankruptcy because it doesn’t carry the same long-term legal or credit consequences. Bankruptcy can stay on your credit report for up to ten years and may impact your future employment or housing options. A management program allows you to pay back what you owe on terms you can actually afford. It’s a less invasive way to regain your financial agency while avoiding the complexities and public record of the court system.
How long does the consolidation process typically take?
The enrollment process for a relief program is typically very fast, often taking only a few days to set up. However, the full journey to becoming debt-free depends on the total amount you owe and your monthly budget. Most programs are structured to resolve your debt within twelve to forty-eight months. You’ll see an immediate reduction in your monthly payment burden, but complete freedom requires staying committed to the methodical repayment schedule designed by your specialists.
Do I need to have a bank account to qualify for consolidation relief?
You do need an active bank account to participate in a consolidation program. This account is necessary because you’ll make a single monthly deposit into a dedicated trust account used to pay your creditors. Having a bank account also allows you to manage your daily expenses more effectively once you’ve stopped the predatory automatic withdrawals. If you’ve had accounts closed due to overdrafts, your specialist can often provide guidance on finding a fresh start with a new account.
Will my credit score improve after I finish the consolidation program?
While we don’t guarantee specific score increases, completing a no credit check payday loan consolidation program significantly improves your financial health. Successfully paying off your debts reduces your total balance and improves your debt-to-income ratio, which are critical factors for your credit profile. By ending the cycle of missed payments and rollovers, you create a stable foundation for future growth. Rebuilding your credit is a natural byproduct of achieving long-term, sustainable debt relief.