The predatory cycle of high-interest debt isn’t a personal failure; it’s a systemic trap designed to keep you paying forever. When you’re facing interest rates exceeding 400% APR and managing five different due dates every month, it feels like you’re just working to fund a lender’s profit margin. You’ve likely watched your bank account dwindle as aggressive ACH withdrawals hit the moment your paycheck arrives. It’s exhausting to live in a state of constant financial high alert. If you’re ready to break this cycle, the most effective path forward is to consolidate online payday loans into a single, manageable structure that puts you back in control.
This guide provides the 2026 roadmap to reclaiming your agency. You’ll discover how to stop the cycle of endless rollovers and protect yourself from predatory collection tactics. We will walk you through the mechanics of combining your debts into one monthly payment while significantly reducing or even stopping the accumulation of interest and fees. By following these proven strategies, you can finally silence the phone calls and focus on building a stable future.
Key Takeaways
- Learn why revoking ACH authorizations is a critical first step to regaining control over your bank account and stopping automatic withdrawals.
- Discover the most effective ways to consolidate online payday loans into one manageable payment without the need for a new high-interest loan.
- Compare the specific eligibility requirements and credit impacts of consolidation loans versus specialized relief programs.
- Follow a structured five-step action plan to inventory your current obligations and stop the cycle of predatory rollovers.
- Understand how professional negotiation can help you reduce or eliminate excessive fees and high-interest charges.
The Trap: Why Online Payday Loans Are Harder to Escape
The mechanics of an online Payday loan are engineered for speed, but that same velocity often accelerates a cycle of debt. While a local storefront requires a physical visit, online lenders use digital signatures and instant bank verification to deposit funds within minutes. This convenience masks a dangerous reality. Online lenders gain a significant technical advantage by requiring Automated Clearing House (ACH) authorization. This allows them to pull funds directly from your bank account the moment your paycheck lands, often before you can cover essential bills like rent or groceries.
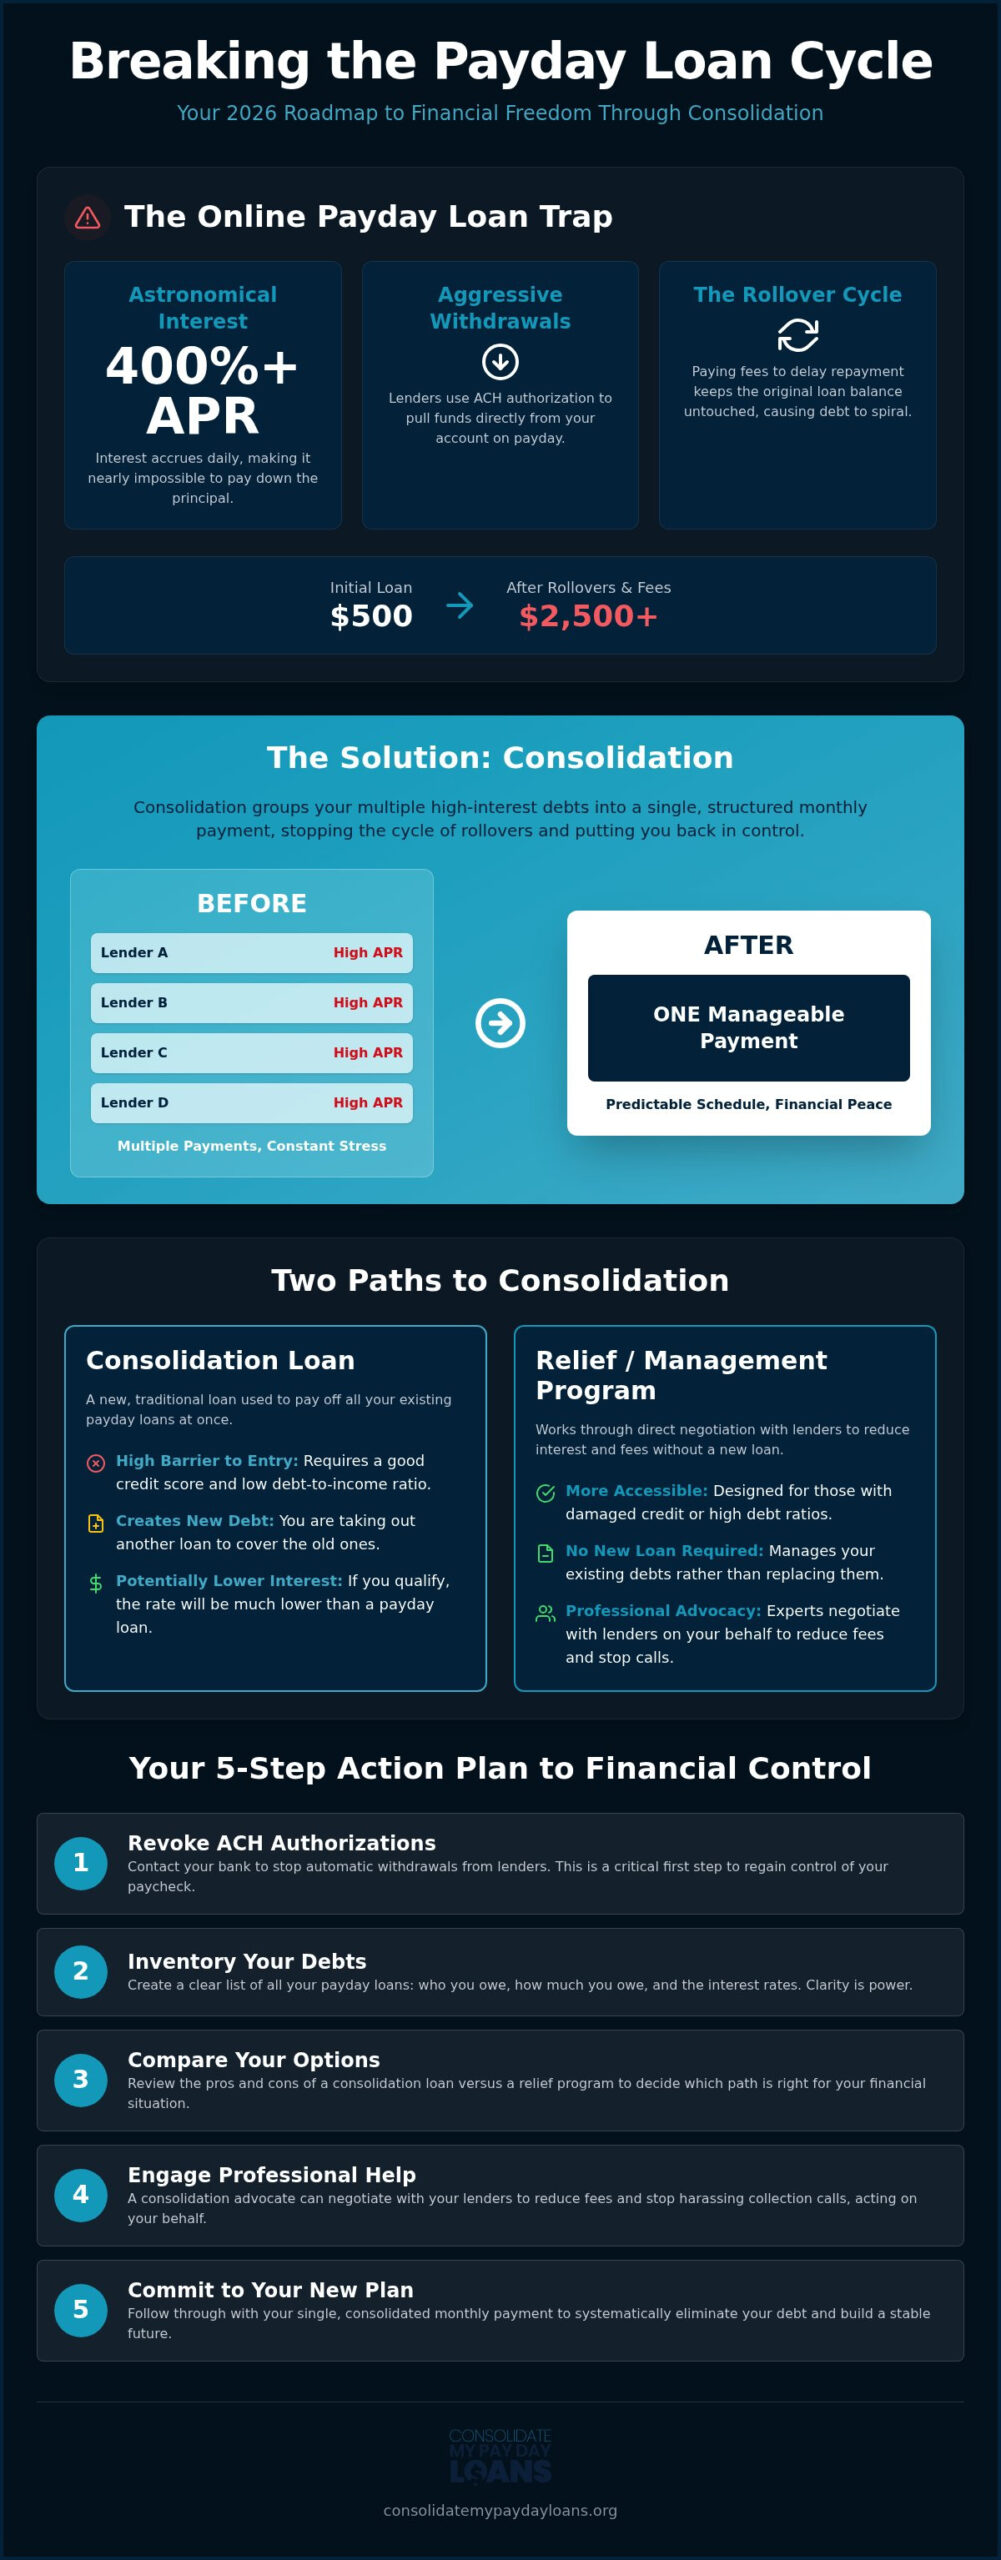
Managing three to five different lenders means juggling multiple due dates and enduring a barrage of bank alerts. It’s a psychological weight that never lifts. The most damaging part of this structure is the “Rollover Trap.” When you can’t pay the full balance, lenders offer to “roll over” the loan for a small fee. This doesn’t reduce what you owe; it merely buys two more weeks at the same astronomical rate. In just a few months, a simple $500 loan can balloon into a $2,500 debt because the principal never decreases. To break this momentum, many borrowers eventually need to consolidate online payday loans into a structured plan that stops the bleeding.
The Reality of 400% APR in the Digital Age
Digital lending platforms often hide the true cost behind “fees per $100 borrowed.” When you calculate the annual percentage rate, it frequently exceeds 400%. This means interest accrues daily at a rate that traditional credit products simply don’t match. The debt treadmill is a state of perpetual repayment where a borrower’s entire payment goes toward interest and fees, leaving the original principal balance untouched. The digital nature of these loans makes it easy to click a button and “renew,” but each click deepens the financial hole.
Why Traditional Banks Say No to Payday Borrowers
You might have already tried to visit a local bank for a personal loan, only to be turned down. Traditional institutions often use an internal banking score that flags frequent payday loan activity as high risk. Even if your credit score is decent, a high debt-to-income ratio caused by multiple short-term loans stalls traditional consolidation efforts. There’s a massive gap between what a bank requires and the reality of someone trapped in high-interest debt. Banks want low risk, but the very nature of these loans makes you look high risk on paper. This is why specialized strategies to consolidate online payday loans are necessary for those who don’t fit the traditional banking mold.
What is Online Payday Loan Consolidation?
Consolidation is the process of grouping multiple high-interest debts into a single, structured monthly payment. Instead of tracking five different lenders with five different due dates, you manage one obligation. This strategy aims to lower the total interest you pay and, more importantly, stop the cycle of endless rollovers that keep you in debt. For many, this represents a strategic alternative to filing for bankruptcy. While bankruptcy stays on your record for years, choosing to consolidate online payday loans allows you to resolve your debt through professional management and negotiation.
The Consumer Financial Protection Bureau often warns about the dangers of the debt trap created by high-cost, short-term lending. Consolidation acts as the exit ramp from that trap. It shifts the power dynamic from the lender back to you. By centralizing your debt, you gain a clear view of your path to zero balance, replacing the chaos of constant bank alerts with a predictable financial schedule.
Consolidation Loans vs. Debt Management Plans
There are two primary ways to achieve this goal. A consolidation loan is a new personal loan used to pay off all your current lenders at once. This requires a decent credit score and a low debt-to-income ratio, which can be difficult for someone already struggling with payday debt. A relief program, however, does not require a new loan. Instead, it works through direct negotiation with your lenders to reduce interest rates and fees. This is often the more accessible path if your credit has already taken a hit from high-interest borrowing. You can use a payday loan consolidation calculator to see how a structured program might change your monthly outlook.
The Role of a Consolidation Advocate
When you enter a consolidation program, you transition from being a “borrower” to a “client.” This shift is significant because you gain an advocate who handles the communication with your lenders. Professional negotiators understand the nuances of the industry and can often stop the aggressive harassment and collection tactics used by online lenders. This centralized communication provides psychological relief, as you no longer have to face predatory lenders on your own. Your advocate works as a protective shield, ensuring that your rights are respected while you focus on regaining your financial agency.
Consolidation Loans vs. Relief Programs: A Direct Comparison
Choosing the right path to consolidate online payday loans depends on your current credit standing and your immediate cash flow needs. While some financial experts suggest taking out a new personal loan to consolidate payday loans, this advice often ignores the reality of those already deep in the debt cycle. A direct comparison between a new loan and a relief program shows that each has a specific role in your recovery. You must weigh the speed of stopping withdrawals against the long-term impact on your credit profile.
A relief program doesn’t require you to take on more debt. Instead, it focuses on managing the debt you already have. This is a critical distinction. A new loan might lower your interest rate, but a relief program can often stop the accrual of fees entirely through professional intervention. When you’re managing multiple online lenders, the speed of stopping bank withdrawals is often more important than a slight credit score bump. Both methods aim for the same result: a single, manageable monthly payment that replaces the chaos of multiple due dates.
When a Consolidation Loan Makes Sense
This route is ideal for borrowers who still have a credit score above 600 and a stable income. It provides the psychological win of seeing every payday balance hit zero in a single day. The primary benefit is simplicity. You replace five payments with one. But be careful. If you don’t cut off the access these lenders have to your accounts and change your borrowing habits, you risk falling back into the same patterns. Using a new loan to pay off old debt only works if you have the discipline to stay away from new high-interest offers.
Why Relief Programs Win for High-Interest Debt
Relief programs are designed for those whom the traditional banking system has left behind. Most payday loan relief programs don’t require a credit check, making them accessible to almost anyone. These programs use aggressive negotiation tactics that a standard personal loan simply cannot match. By focusing on the predatory nature of the original contracts, relief specialists can often secure terms that prioritize your survival over the lender’s profit margin. This is often the most realistic way to break the cycle when interest rates have already destroyed your debt-to-income ratio.
How to Consolidate Online Payday Loans: A 5-Step Action Plan
Breaking the cycle requires more than just good intentions; it requires a tactical shift. To effectively consolidate online payday loans, you must transition from a defensive posture to an offensive one. This starts with a clear inventory of every lender, balance, and interest rate. You can use a payday loan consolidation calculator to visualize the total cost of your current path compared to a structured relief program. Once you see the numbers, the need for a professional consultation becomes clear. The final steps involve committing to a single, manageable payment plan and ensuring those predatory accounts are closed for good. This prevents the temptation to re-borrow while you’re still in the recovery phase.
Step 1: Revoking ACH Access and Stopping the Drain
Online lenders rely on the speed of Automated Clearing House (ACH) withdrawals to drain your account before you can prioritize your needs. Under the Electronic Fund Transfer Act, you have the legal right to stop these automatic pulls. You must send a formal revocation letter to both the lender and your bank to make this effective. While stopping a payment applies to a single transaction, revoking authorization legally cancels the lender’s right to access your account for all future withdrawals. This simple act restores your agency over your own paycheck and prevents the “overdraft cascade” that often follows predatory withdrawals.
Step 2: Professional Negotiation and Hardship Programs
Once the immediate drain is stopped, the focus shifts to reducing the actual balance. Experts leverage specialized payday loan hardship programs to negotiate lower settlements or interest waivers that individuals rarely obtain on their own. Professional debt management services also utilize “cease and desist” powers to stop the relentless collection calls that fuel your stress. Lenders are often more willing to negotiate with third-party agencies because it signals that the borrower is committed to a structured resolution rather than a total default. This professional intervention transforms a chaotic struggle into a predictable exit strategy, allowing you to pay back what you owe on terms you can actually afford.
If you’re tired of watching your hard-earned money vanish every payday, it’s time to take the first step toward a solution. Start your recovery journey by exploring our specialized consolidation programs today.
Regaining Financial Peace with Consolidate My Payday Loans
Financial turbulence doesn’t have to be your permanent reality. At Consolidate My Payday Loans, we provide a non-judgmental environment where your recovery is the priority. Many general debt companies treat payday loans as an afterthought, but we specialize specifically in this high-interest sector. We understand the aggressive nature of online lenders and the specific mechanics they use to keep you trapped. By choosing to consolidate online payday loans through our structured model, you replace chaos with a predictable, single monthly payment. Your journey starts with a confidential debt assessment that respects your privacy and your pace.
Our approach is designed to simplify your life immediately. We act as a protective shield between you and predatory collection tactics, allowing you to breathe again. Instead of juggling multiple high-interest obligations, you focus on one manageable path toward zero balance. This consolidated model isn’t just about the numbers; it’s about reclaiming your time and mental energy. You’ve spent enough time worrying about the next bank withdrawal. It’s time to focus on your recovery.
Why Our Experience Since 2004 Matters
Operating since 2004 under Solid Ground Financial, we’ve navigated decades of shifting regulations in the lending industry. This longevity provides us with the expertise needed to protect our clients from evolving predatory practices. We’ve refined proven strategies for payday loan consolidation that address the unique challenges of digital lenders. Our “Solid Ground” advantage means you have a stable partner who won’t be surprised by lender tactics. We’ve seen every strategy used by high-interest companies, and we know how to counter them effectively to secure your financial freedom.
Your Future Beyond the Payday Loan Cycle
Imagine a life where your paycheck stays in your pocket. Once the high interest is gone, you can finally build the emergency fund that prevents future borrowing. This transition often leads to more traditional financial health, where you can focus on long-term savings or even traditional credit card consolidation strategies if needed. The psychological relief of a zero-payday-debt lifestyle is profound. You’ll regain your personal agency and the peace of mind that comes with true financial stability. We’re here to help you reach that finish line and stay there. Your future is waiting, and it’s free from the burden of high-interest debt.
Your Path to a Debt-Free Future Starts Today
Breaking free from high-interest lending requires a combination of tactical action and professional support. You’ve learned how to revoke ACH access to protect your income and why specialized relief programs often outperform traditional loans for those trapped in the debt cycle. The most important step is recognizing that you don’t have to face predatory lenders alone. By choosing to consolidate online payday loans, you’re not just managing debt; you’re reclaiming your personal agency and psychological peace.
Since 2004, our expert negotiators have provided empathy-first financial guidance to help individuals navigate their most turbulent times. We offer a no-obligation debt assessment to help you understand your options without any added pressure. You can take control of your financial narrative right now. Estimate your savings with our Payday Loan Consolidation Calculator and see exactly how a structured plan can change your outlook. A stable, debt-free life is within your reach, and we’re ready to help you build it.
Frequently Asked Questions
Can I consolidate online payday loans with bad credit?
Yes, you can. Specialized relief programs are specifically designed for individuals who may not qualify for traditional bank loans due to their credit history. These programs prioritize your current income and your commitment to a structured repayment plan rather than a three-digit score. This allows you to consolidate online payday loans even if your credit has been damaged by high-interest lending practices in the past.
How do I stop an online payday lender from taking money out of my account?
You have the legal right to stop automatic withdrawals by revoking your ACH authorization. To do this, you must notify the lender in writing and inform your bank that you have canceled the authorization. It’s best to do this at least three business days before your next payday. This action regains control of your bank account and prevents lenders from draining your funds before you can pay essential bills.
Will consolidating my payday loans hurt my credit score?
Consolidation can have a varied impact on your credit. If you use a relief program, you might see a temporary dip as lenders close accounts and report the new payment status. However, the long-term benefits are far more significant. By stopping the cycle of late fees and high interest, you create a foundation for a healthy credit recovery. Most clients find that their scores improve once they successfully eliminate their payday debt.
What is the difference between payday loan consolidation and settlement?
Consolidation merges your debts into one manageable payment while focusing on reducing interest and stopping rollovers. Settlement is a different process where you negotiate to pay a single lump sum that is less than the total balance. While settlement can reduce the principal, it often requires you to fall behind on payments first. Consolidation offers a more stable, structured path that protects you from the aggressive collection tactics associated with default.
Are online payday loan consolidation companies legitimate?
Legitimacy in this industry is found through experience and transparency. Look for companies that have been in operation for many years, such as those established under Solid Ground Financial in 2004. Legitimate companies will provide a clear, no-obligation debt assessment and won’t make unrealistic promises about erasing debt overnight. They act as your advocate, using professional negotiation to help you consolidate online payday loans into a plan that actually fits your budget.
How much can I save by using a payday loan consolidation calculator?
A payday loan consolidation calculator is a transparency tool that helps you estimate your potential savings. By entering your current balances and interest rates, you can see how much of your money is going toward fees versus principal. Many borrowers discover they can save thousands of dollars in interest over the life of their debt. It’s a powerful way to visualize the tangible benefits of moving toward a structured relief program.
What happens if I can’t afford my consolidated payment?
If your financial situation changes, the first step is to communicate with your debt advocate. Legitimate programs offer a level of flexibility that predatory lenders do not. Your advocate can often work with lenders to adjust your payment schedule or find a temporary hardship solution. The goal is to keep you moving forward so you don’t feel forced to return to the high-interest lending cycle during a difficult month.
Is consolidation a better option than filing for bankruptcy for payday loans?
Consolidation is often a better first step because it doesn’t carry the severe, decade-long stigma of bankruptcy. While bankruptcy is a legal process for total insolvency, consolidation is a proactive strategy to resolve your debt through negotiation. It allows you to pay back your obligations on better terms while keeping your financial record cleaner. For many, this provides the psychological relief they need without the long-term restrictions on their personal agency.