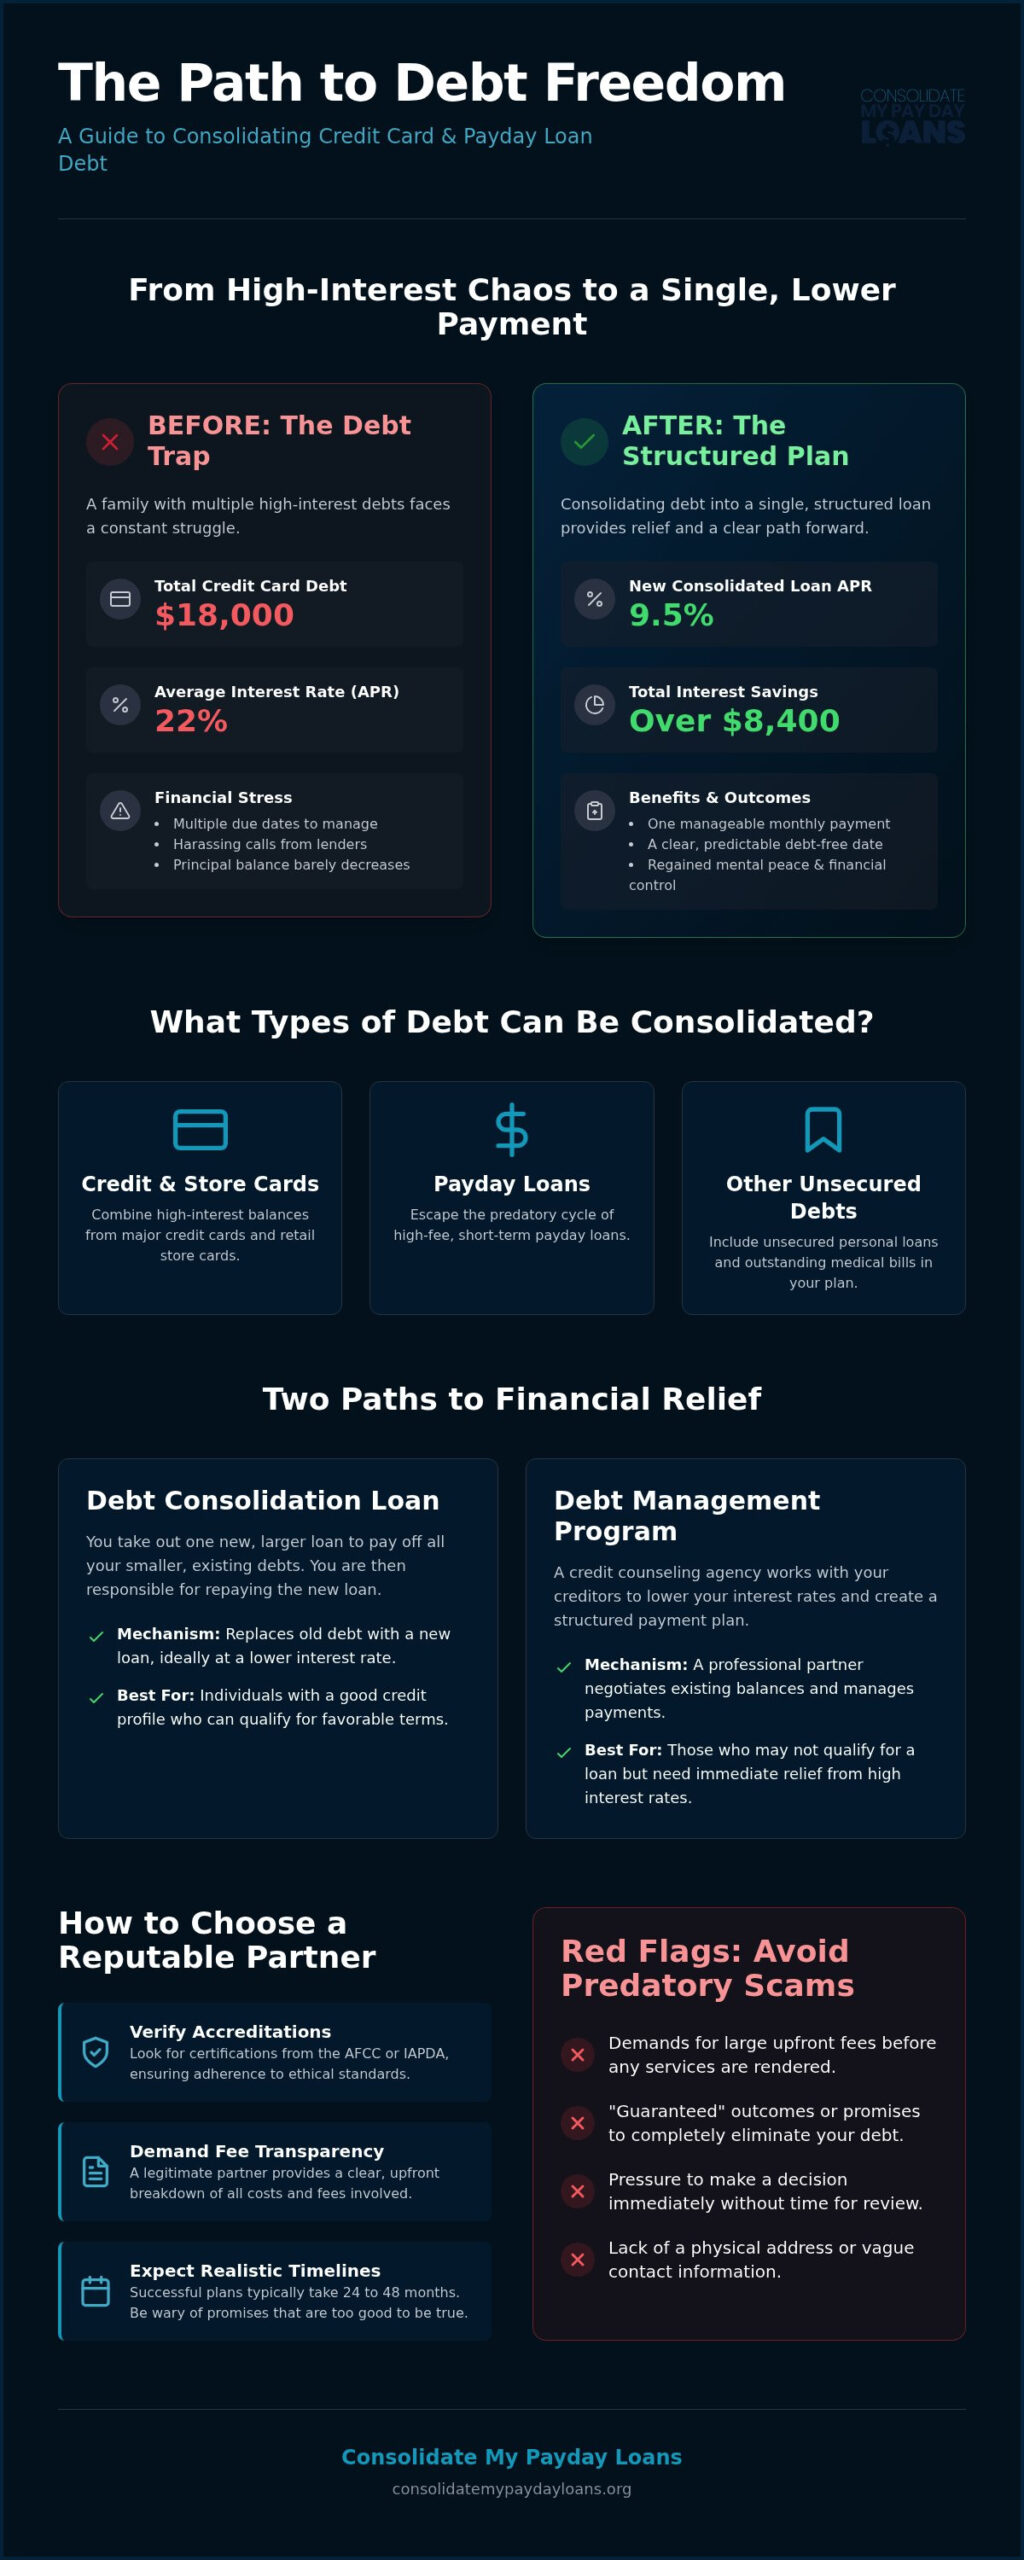
A family carrying $18,000 in credit card debt at a 22% interest rate could save over $8,400 in interest alone by switching to a structured 9.5% APR loan. It’s a staggering figure that highlights exactly why finding the right credit card consolidation companies is so vital in 2026. You’re likely tired of watching your entire paycheck vanish into a black hole of high interest rates while trying to manage multiple, conflicting due dates every month.
It’s exhausting to field harassing calls from lenders and feel the constant weight of financial uncertainty. We understand the confusion that comes from trying to distinguish between legitimate relief and predatory scams that only deepen the debt trap. You deserve a partner who prioritizes your recovery over their own profit margins; someone who acts as a stable anchor while you navigate these turbulent waters.
This article provides a strategic path to merge your credit card and payday loan debt into one manageable plan. You’ll discover how to identify reputable consolidation partners that offer a single, lower monthly payment and a clear end to the cycle of late fees. We’ll break down the latest 2026 lender trends and the specific red flags you must avoid to reclaim your mental peace and financial agency.
Key Takeaways
- Learn how reputable credit card consolidation companies streamline your monthly obligations by negotiating lower rates or securing more manageable interest terms.
- Identify legitimate partners by verifying industry accreditations like the AFCC or IAPDA and checking for full fee transparency.
- Determine whether a consolidation loan or a debt management program is the most effective tool for your specific credit profile and debt-to-income ratio.
- Recognize dangerous red flags, such as demands for upfront fees or “guaranteed” outcomes, to avoid falling into predatory lending traps.
- Discover how a unified exit strategy can help you manage credit cards and payday loans simultaneously to finally stop the cycle of high-interest debt.
What Do Credit Card Consolidation Companies Actually Do?
Credit card consolidation companies act as a stable anchor for those caught in a cycle of high-interest debt. These organizations specialize in streamlining multiple unsecured obligations into one single monthly payment. It’s a process designed to simplify your financial life and provide immediate breathing room. According to this Debt consolidation overview, the primary objective is to reduce the overall cost of borrowing. In 2026, this has become a vital survival tactic as interest rate volatility continues to squeeze household budgets and erode personal savings.
The core mechanism of these companies involves either providing a new, lower-interest loan or negotiating directly with creditors to reduce rates. You must recognize the difference between refinancing and relief. Refinancing is essentially swapping old debt for a new loan with better terms; it typically requires a strong credit profile to be effective. Relief is a management strategy where a professional partner negotiates your existing balances. For many families, the relief model is the only realistic way to stop the bleeding when interest rates have already outpaced their monthly income. This distinction is critical because choosing the wrong path can lead to further financial strain rather than the recovery you’re seeking.
The Role of a Debt Consolidator
A debt consolidator functions as your dedicated advocate and intermediary. They handle the difficult conversations with lenders so you don’t have to deal with harassing phone calls or aggressive collection tactics. By merging your debts, they eliminate the mental clutter of managing multiple due dates and varying interest calculations. This structured approach gives you a definitive end date for your debt. You gain a clear, predictable roadmap to financial freedom. Instead of wandering through a maze of minimum payments, you follow a methodical plan that prioritizes your debt-free date.
Common Debts Covered by Consolidation
Most programs focus on high-interest credit card balances and retail store cards that often carry APRs exceeding 30%. You can also include unsecured personal loans and unpaid medical bills in these plans. A significant advantage of working with specialized credit card consolidation companies is their ability to address complex burdens like consolidating payday loans. While traditional lenders might turn you away due to these high-risk obligations, a legitimate consolidation partner understands how to dismantle these traps. This ensures that every dollar you pay actually reduces your principal balance, allowing you to regain agency over your financial life.
How to Evaluate and Compare Consolidation Providers
Selecting the right partner among various credit card consolidation companies requires a cautious and methodical approach. You need to ensure a provider acts as an advocate for your recovery rather than a source of more debt. Start by verifying industry accreditations from the American Fair Credit Council (AFCC) or the International Association of Professional Debt Arbitrators (IAPDA). These certifications prove a company follows strict ethical guidelines and legal standards. It’s also vital to review the Consumer Financial Protection Bureau’s advice on consolidating credit card debt to understand how different programs impact your financial health.
Transparency is the cornerstone of any partnership with credit card consolidation companies. A legitimate provider will offer a clear breakdown of all fees and the total cost of the program from the very beginning. Be wary of any company that promises a “debt-free date” that sounds too good to be true. Most successful plans take 24 to 48 months to complete. If a salesperson promises you’ll be clear in six months without a massive lump-sum payment, they’re likely not being honest. For those trapped in high-interest cycles, ensure the provider offers a specialized payday loan hardship program to address the most aggressive forms of debt.
Verification Checklist for Legitimacy
Before sharing personal financial data, confirm the company is registered to operate in your specific state. A physical office and a long history of service are powerful indicators of stability. For instance, companies operated under established firms like Solid Ground Financial, which has been in business since 2004, offer a level of security that new, online-only startups cannot match. Don’t rely solely on the company’s website for praise. Check independent review platforms to see how they handle customer support during the middle of a program when things get challenging.
The Importance of a Preliminary Consultation
You should never sign a contract without a detailed debt analysis. A professional consultant will review your income, expenses, and specific creditors to build a realistic plan. Ask them exactly how they handle aggressive lenders who may continue to call during the early stages of the program. They should also provide tools like a payday loan consolidation calculator to model your potential savings. Seeing the numbers on paper helps you make an informed decision based on facts rather than emotions. If you’re ready to see how these strategies apply to your situation, you can explore your relief options with a trusted expert today.
Debt Consolidation Loans vs. Debt Management Programs
Choosing between a new loan and a management program is the most critical decision you’ll make in your recovery journey. While many people hope for a simple bank loan, your credit score and debt-to-income ratio often dictate which path is actually available. This Consumer Financial Protection Bureau guide highlights that understanding the trade-offs is vital before you commit. Credit card consolidation companies help you navigate these options, but the best choice depends on whether you’re looking for a lower interest rate or a complete financial overhaul.
A consolidation loan involves taking out a new personal loan to pay off your existing cards. This is a refinancing strategy that works best if you have a FICO score above 660. In 2026, lenders like Happen Bank offer APRs starting at 6.53%, while LightStream offers rates from 7.24%. However, if your score has already taken a hit, you might face APRs as high as 35.99% or origination fees up to 9.99% at lenders like Upgrade. If the new interest rate isn’t significantly lower than your current average, a loan might just move your debt around rather than solving the problem.
Pros and Cons of Consolidation Loans
- Pro: You receive a fixed monthly payment and a predictable schedule to become debt-free.
- Con: You run the risk of running up your credit card balances again if you don’t change your spending habits.
- Requirement: Competitive rates usually require a strong credit profile and a low debt-to-income ratio.
For those trapped in a cycle of high-interest payday debt or those who don’t qualify for traditional bank loans, a debt management program is often the superior choice. This isn’t a new loan; it’s a structured repayment plan where your partner negotiates directly with your creditors to lower rates and waive fees. This strategy serves as a powerful payday loan consolidation instead of bankruptcy option. It allows you to resolve high-risk obligations without the long-term legal stigma of a court filing, providing a safer alternative for individual recovery.
Pros and Cons of Debt Management Plans (DMPs)
- Pro: No new loan is required; your partner works with your existing lenders to simplify your obligations.
- Pro: These programs can include predatory payday loans that traditional credit card consolidation companies often ignore.
- Con: You’ll likely be required to close your credit card accounts while you’re enrolled in the program.
Both paths impact your credit score differently. A loan causes a temporary dip due to a hard inquiry but can help long-term by improving your credit utilization. A management plan might lower your score initially as accounts close, but it builds a foundation for lasting financial agency. The goal is to stop the cycle of late fees and find a manageable way forward.
Red Flags: Avoiding Predatory Consolidation Scams
When you’re drowning in debt, a lifeline looks like a miracle. However, predatory actors often pose as legitimate credit card consolidation companies to exploit this vulnerability. You must remain vigilant to ensure your path to recovery doesn’t lead to a deeper trap. Scammers thrive on the stress of high interest rates and harassing calls, offering “guaranteed” results that no honest company can promise. Real recovery depends on your specific financial profile; anyone claiming otherwise is likely leading you toward a scam.
The ‘Upfront Fee’ Warning
Legitimate debt relief providers don’t get paid until they’ve actually delivered results. The Federal Trade Commission’s Telemarketing Sales Rule is a critical consumer protection that prohibits debt relief companies from charging upfront fees before they settle or reduce your debt. If a company demands a large initial payment before performing any service, walk away immediately. Legitimate firms typically structure their fees based on performance or through a transparent monthly service model once you’ve officially started the program. Predatory lending is a practice that intentionally traps borrowers in a cycle of debt.
Analyzing the ‘Too Good to Be True’ Offer
Marketing slogans that promise to “cut your debt by 80%” are almost always misleading. These claims usually refer to debt settlement, which is fundamentally different from the structured approach of true consolidation. While settlement involves letting accounts go delinquent to negotiate a lump sum, consolidation focuses on managing and reducing interest while paying back the principal. You should also verify if a company is actually affiliated with the lenders they claim to negotiate with. Many scammers fabricate these relationships to build false trust and rush you into a contract.
Watch out for high-pressure sales reps who discourage you from reading the fine print. A common predatory tactic is the “new loan” trap. Here, a company offers to consolidate your debt but simply rolls you into another high-interest product with hidden fees. This doesn’t solve the problem; it just changes the name of the lender while keeping you in a cycle of financial turbulence. Don’t let aggressive tactics force you into a bad decision. You can connect with a transparent debt expert who prioritizes your long-term financial health over quick profits today.
A Unified Strategy for Credit Cards and Payday Loans
Managing multiple high-interest obligations feels like trying to stay afloat while tied to a heavy anchor. In many cases, payday loans are that anchor. They create a volatile financial environment that makes it impossible to pay down your credit card balances. While many credit card consolidation companies only address traditional bank debt, a truly effective recovery plan requires a unified exit strategy. This approach looks at your entire financial picture to ensure no single debt source can pull you back into the cycle of insolvency.
Prioritizing your debt is the first step toward regaining your agency. You cannot simply throw money at every balance and hope for the best. You need a methodical system that identifies which lenders are the most aggressive and which interest rates are doing the most damage. Professional advocacy plays a huge role here. Having an expert guide who understands the systemic traps of the lending industry provides a sense of calm reassurance. It transforms a chaotic struggle into a structured path toward psychological peace and tangible financial improvement.
Stopping the Payday Loan Cycle First
Payday loans must be your immediate priority. These lenders often secure ACH authorizations that allow them to drain your bank account the moment your paycheck is deposited. This leaves you with nothing for essential living expenses, which often forces you back into taking another loan. Consolidation stops this rollover trap. It prevents interest from compounding weekly and gives you a chance to breathe. Accessing specialized payday loan relief creates the immediate cash flow you need to fund the rest of your consolidation plan. You’re no longer just surviving; you’re actively managing your recovery.
Long-Term Credit Card Stability
Once the volatility of payday debt is under control, you can focus on long-term credit card stability. You must shift from a “minimum payment” mindset to one focused on principal reduction. Minimum payments on high-interest cards are designed to keep you in debt for decades. A single, manageable payment plan ensures you never miss a due date or incur another late fee. This simplicity reduces the mental load of debt management significantly. Your next step is to obtain a free debt analysis. Seeing your potential savings modeled out provides the momentum needed to cross the finish line. You’ve spent long enough under the weight of predatory interest; it’s time to reclaim your financial future.
Reclaim Your Financial Agency in 2026
Choosing between various credit card consolidation companies requires more than just comparing interest rates; it demands a partner who understands the systemic traps of predatory lending. You’ve learned how to verify industry accreditations and why managing payday loans first is essential to stopping the cycle of debt. By focusing on a unified exit strategy, you can finally move from the exhaustion of minimum payments to a clear, structured path toward principal reduction.
As specialized high-interest debt experts, we provide non-judgmental financial advocacy rooted in over two decades of debt management experience via Solid Ground Financial. We act as a stable anchor while you navigate the path to recovery and regain control over your financial life. Estimate your savings and start your recovery with our consolidation tools today. You don’t have to face this turbulence alone; relief is within your reach and a debt-free future is possible.
Frequently Asked Questions
Is it a good idea to consolidate credit card debt?
Consolidating is a strategic move if your current interest rates make it impossible to reduce your principal balance. It simplifies your life by merging multiple due dates into one manageable monthly obligation. This approach helps you escape the cycle of minimum payments that keeps families in debt for decades. You’ll gain a clear roadmap to freedom; however, you must also commit to changing the spending habits that led to the debt initially.
How much does it cost to use a debt consolidation company?
Legitimate credit card consolidation companies don’t charge upfront fees due to strict federal regulations. Instead, they typically earn revenue through monthly administrative fees or a percentage of the debt they successfully manage for you. You should always receive a transparent breakdown of these costs during your initial consultation. Be cautious of any organization that isn’t completely open about their fee structure or demands payment before they’ve provided any real relief.
Will credit card consolidation hurt my credit score?
You may notice a temporary dip in your score when you first start. This happens because of hard inquiries for new loans or the closing of accounts during a management program. Over time, however, consolidation usually improves your score by establishing a history of consistent, on-time payments. It also reduces your overall credit utilization ratio. This structured recovery builds a much stronger financial foundation than struggling with missed payments and late fees.
Can I consolidate my payday loans and credit cards together?
Yes, merging these different types of unsecured debt is a highly effective way to regain control. Specialized providers like Consolidate My Payday Loans focus on this unified strategy because payday debt often acts as an anchor that prevents credit card payoff. By combining them, you stop predatory interest cycles and protect your bank account from aggressive withdrawals. This single payment approach ensures your recovery isn’t sabotaged by the high volatility of payday lending traps.
What happens if I can’t qualify for a consolidation loan?
If your credit score prevents you from getting a new loan, a debt management or relief program is your best alternative. These plans don’t rely on your credit score; instead, they focus on direct negotiation with your existing creditors. Your advocate works to lower interest rates and waive burdensome fees without requiring you to take on new debt. This is often a safer path for individuals who have been rejected by traditional banks or credit unions.
How do I know if a debt consolidation company is legitimate?
Verify that the company holds accreditations from organizations like the AFCC or IAPDA. Legitimate partners, such as those operating under Solid Ground Financial since 2004, will have a verifiable history and a physical office. They won’t use high-pressure sales tactics or guarantee impossible results. A reputable provider acts as a protective expert and will always prioritize your debt-free date over their own profit margins while offering a non-judgmental environment for your recovery.
Can I still use my credit cards after I consolidate them?
Most management programs require you to stop using your cards and close the accounts to prevent new debt from accumulating. While this might feel restrictive, it’s a vital step in breaking the cycle of high-interest borrowing. If you use a loan to consolidate, your accounts might stay open, but using them again is dangerous. The goal is to move from a mindset of borrowing to one of principal reduction and long-term financial stability.
How long does the consolidation process typically take?
Most structured debt plans take between 24 and 48 months to reach completion. Your specific timeline depends on the total amount you owe and how much you can realistically afford to pay each month. While this isn’t an instant fix, it provides a predictable and methodical path that minimum payments can never offer. You’ll work through a steady progression that builds confidence and ensures you have a definitive date for your total financial freedom.