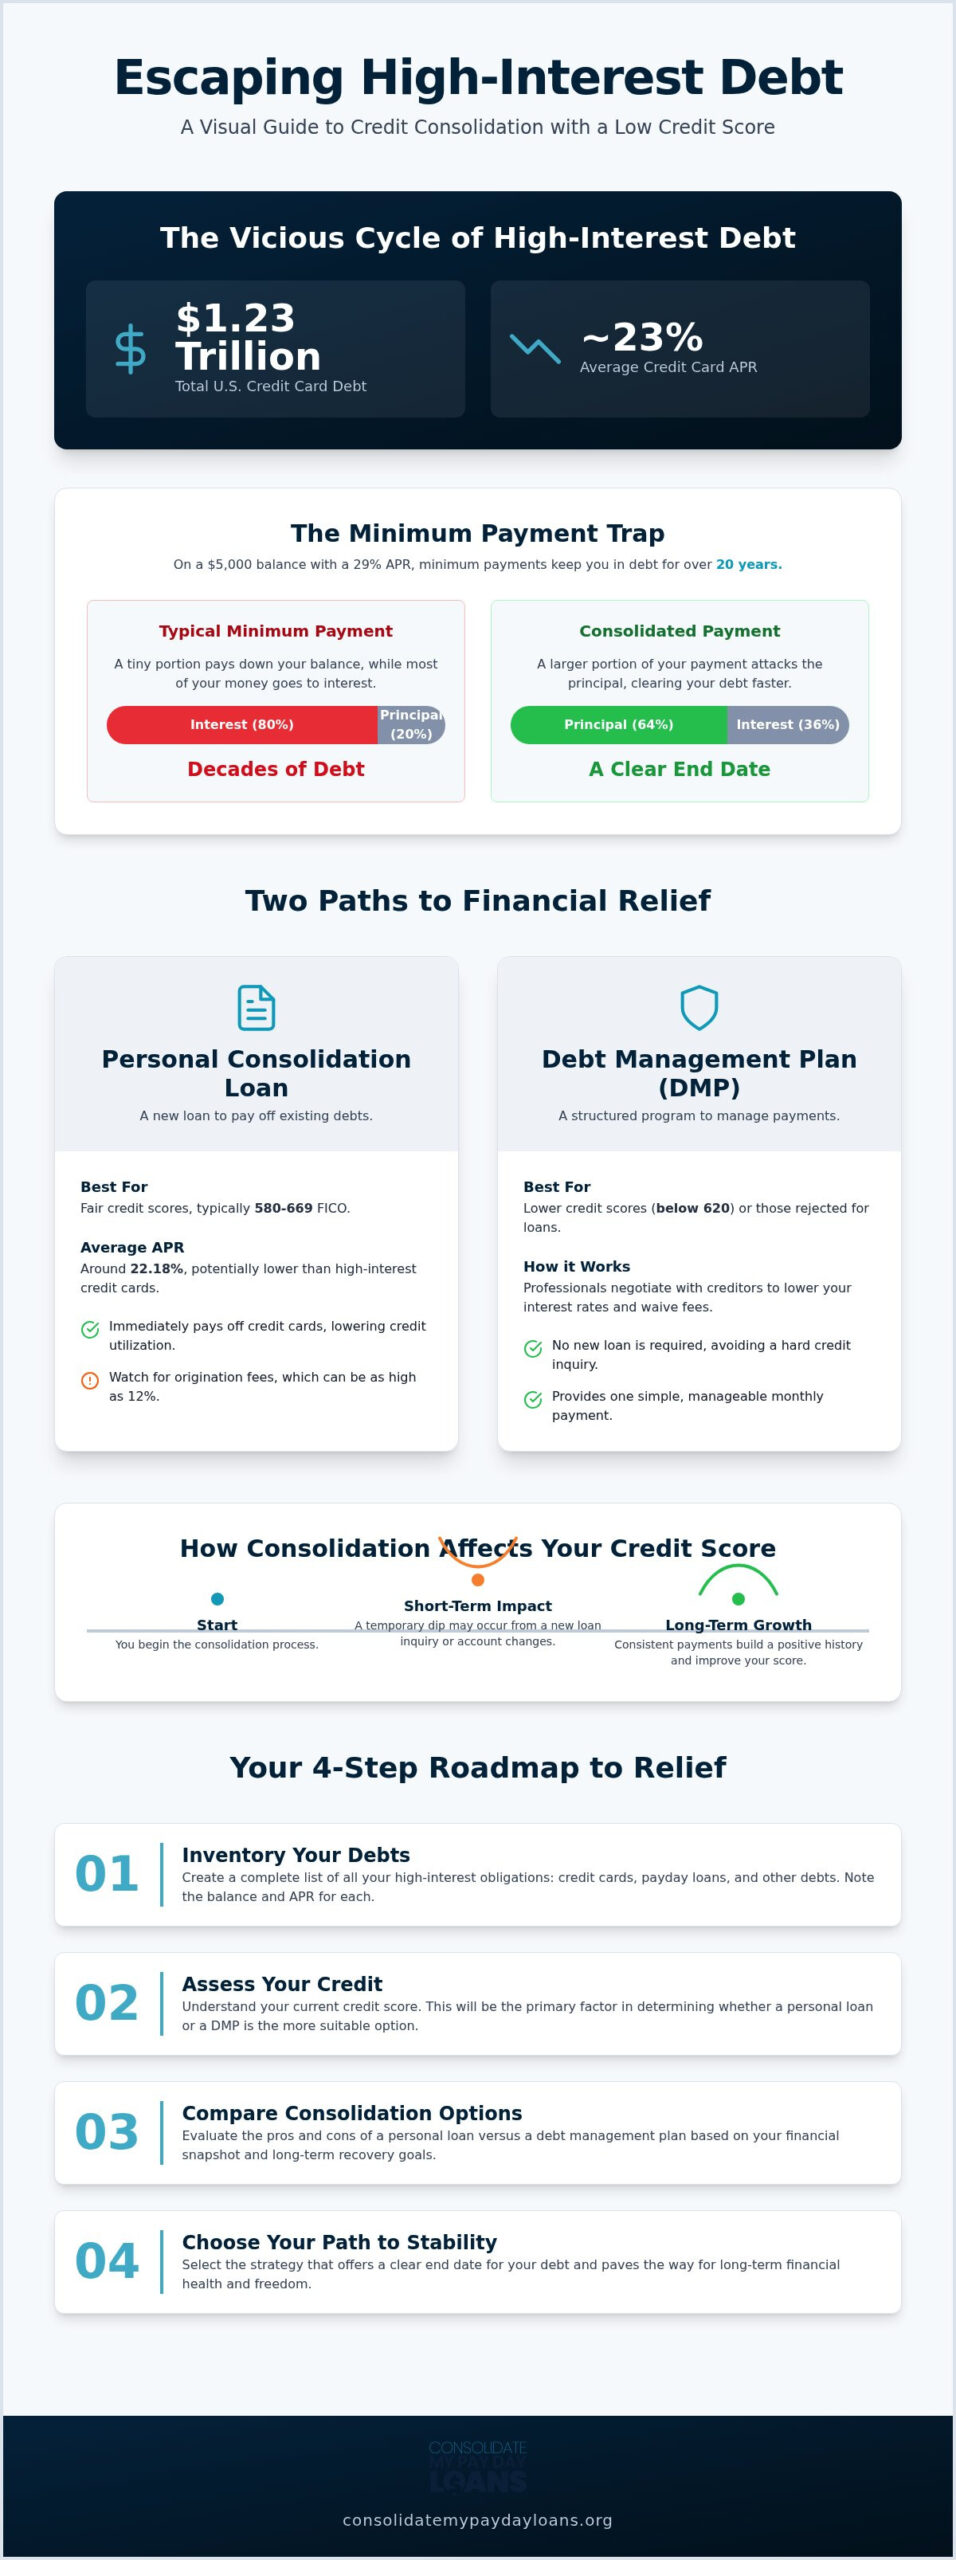
With total U.S. credit card debt reaching a staggering $1.23 trillion in 2026, you aren’t alone if you feel like you’re drowning in high-interest payments. Finding effective credit card consolidation for bad credit often feels impossible when traditional lenders only see a three-digit number rather than your actual financial potential. We understand the crushing weight of daily collection calls and the fear that bankruptcy is your only remaining option. It’s exhausting to watch high APRs, which now average nearly 23 percent, swallow every dollar you earn while your principal balance barely moves.
You’ve likely felt that the system is designed to keep you stuck, but there’s a path toward stability. You can merge your high-interest obligations into a single, lower monthly payment even with a low credit score. This article will show you how to bypass predatory lending cycles and secure a clear end date for your debt. We’ll examine the mechanics of debt management programs, the reality of 2026 interest rates, and the specific strategies used to negotiate with creditors to stop the cycle of late fees for good.
Key Takeaways
- Learn why credit card consolidation for bad credit is still achievable even with a score below 620 by exploring alternatives to traditional bank loans.
- Compare the immediate payoff of a personal loan with the structured support of a debt management plan to determine which fits your recovery goals.
- Understand the temporary impact consolidation has on your credit score and how it paves the way for long-term financial health.
- Follow a practical roadmap to qualify for relief when lenders say no, starting with a complete inventory of your high-interest obligations.
- Discover why merging credit card debt with payday loans creates a stronger, more resilient exit strategy against predatory lending cycles.
Understanding Credit Card Consolidation with a Low Credit Score
Credit card consolidation is the strategic process of merging multiple high-interest balances into a single, manageable payment. For many, this sounds like a logical path to relief, yet those with a credit score below the 620 to 640 range often find themselves locked out of traditional bank options. This is where credit card consolidation for bad credit becomes a specialized necessity rather than just a simple loan application. When your APRs climb toward 25% or 30%, your monthly payments stop being a tool for progress and start acting as a permanent anchor. Understanding Debt Consolidation is the first step in realizing that debt relief is a broad umbrella. It includes programs and structures designed to help you regain agency without requiring a perfect financial history.
The Problem with the Minimum Payment Cycle
The minimum payment cycle is a mathematical trap designed to favor the lender. When you pay only the minimum, you’re primarily servicing the interest while the principal balance remains nearly untouched. Consider a $5,000 balance on a card with a 29% APR. If you only make the minimum payments, it could take you over 20 years to pay off that single debt. You would end up paying thousands more in interest than you originally borrowed. This cycle creates a profound psychological toll. It’s demoralizing to work hard all month only to see your balances stay the same after you’ve sent off your hard-earned money. Breaking this cycle requires a shift from passive payments to active management.
Why Traditional Lenders Reject Bad Credit Applicants
Banks and traditional lenders rely heavily on automated systems that prioritize your credit score and Debt-to-Income (DTI) ratio. If your score is low, they view you as a high-risk liability. High credit utilization, which occurs when your cards are maxed out, signals to a bank that you’re overextended and potentially unable to handle new credit. Even if you have a steady income, a DTI ratio above 43% often triggers an automatic rejection. These institutions aren’t looking at your potential for recovery; they’re looking at a static snapshot of your past struggles. This is why you need an advocate who understands the nuances of credit card consolidation for bad credit and can offer paths that banks simply won’t consider.
Personal Loans vs. Debt Management Plans for Bad Credit
When you’re searching for credit card consolidation for bad credit, you’re essentially choosing between two distinct strategies. One involves taking out a new loan to wipe the balances clean. The other utilizes a structured management plan to lower your existing rates through professional negotiation. Both paths aim for the same result: a single monthly payment and a clear end date. However, the right choice depends heavily on how your credit score has been impacted by your current debt load. If your score is too low for a standard bank loan, you don’t have to give up on the idea of merging your debts.
When a Consolidation Loan Makes Sense
If your FICO score sits between 580 and 669, you might still qualify for a personal loan. In 2026, the average APR for these loans is approximately 22.18%. This can be a viable move if your current credit card interest rates are hovering around 29% or higher. A loan provides an immediate payoff of your cards, which can boost your credit score by lowering your utilization ratio. You must be cautious, though. Many lenders charge origination fees as high as 12% of the total loan amount. These hidden costs can eat into your savings before you’ve even made your first payment. Always ensure the total cost of the new loan is lower than the interest you’d pay on your cards. You can explore various debt consolidation options through credit unions, which often offer more favorable terms than big banks.
The Benefits of a Debt Relief Program
For those who have been rejected by traditional lenders, credit card consolidation for bad credit often takes the form of a Debt Management Plan (DMP). This isn’t a new loan. Instead, it’s a structured program where professional negotiators work directly with your creditors. They aim to lower your interest rates and waive late fees, making your debt actually payable. One of the biggest advantages is that DMPs don’t require a high credit score for qualification. You get the convenience of a single payment without the stress of a hard credit inquiry. This approach mirrors the logic of payday loan relief, focusing on systemic management rather than more borrowing. By choosing a program that prioritizes advocacy, you protect yourself from the predatory lending cycles that often target people with bad credit. If you’re tired of seeing your balances grow despite your best efforts, you can use a debt management strategy to finally regain your financial agency.
How Credit Consolidation Affects Your Credit Score
Many people hesitate to pursue credit card consolidation for bad credit because they fear it will permanently damage their credit score. This concern is understandable. You’ve worked hard to keep things afloat, and the last thing you want is more red ink on your financial record. However, it’s essential to distinguish between a temporary dip and a long-term strategy for recovery. While starting a program or applying for a loan might cause a minor, short-term decrease in your score, the alternative of staying in a high-interest trap is far more damaging. We don’t offer credit repair services; instead, we focus on debt consolidation, which addresses the underlying debt load rather than just the reporting of it.
Utilization and the 30% Rule
The utilization ratio is the amount of revolving credit you’re currently using divided by your total available credit limits. It accounts for 30% of your total credit score. When your cards are maxed out, your utilization is 100%, which signals high risk to lenders. By consolidating those balances, you effectively bring those individual card balances toward zero. This immediate drop in utilization often results in a significant score increase over several months. To maximize this benefit, it’s generally better to keep your accounts open but inactive. Closing them can reduce your total available credit and accidentally spike your ratio again. You’re in control of this balance.
The Power of On-Time Payment History
Your payment history is the single most important factor in your credit score, making up 35% of the total calculation. When you’re juggling five different due dates and five different minimum payments, the risk of a missed deadline is incredibly high. A single late payment can stay on your report for seven years. If you are looking at credit card consolidation for bad credit, the primary benefit is simplification. Consolidation reduces those variables down to one manageable monthly payment. This structure allows for easy automation, ensuring you never miss a date. This predictability provides psychological peace of mind and builds a consistent, positive history that lenders value. You aren’t just paying down debt; you’re actively demonstrating financial reliability.
Qualifying for Consolidation When Lenders Say No
Facing a rejection from a bank feels like hitting a brick wall. When you’re seeking credit card consolidation for bad credit, a “no” from a traditional lender isn’t the end of your story. It’s simply a sign that you’re looking in the wrong place. Banks use rigid algorithms that don’t account for your determination to change. Relief programs, however, use human advocacy to find a path forward. If your score has fallen below the threshold for a standard personal loan, you need a specialized roadmap to regain your financial agency.
Your first step is to document every single debt you owe without exception. This includes your credit card balances and any high-interest payday loans that might be draining your accounts. Next, use a payday loan consolidation calculator to get a clear, unvarnished look at your total debt load. Seeing the numbers in one place can be intimidating, but it’s a necessary part of the healing process. Third, seek a specialized debt management advocate instead of a traditional bank. These experts have the industry connections to negotiate with creditors on your behalf. Finally, review your monthly budget with a critical eye. You must ensure the proposed single payment is sustainable so you don’t fall back into old patterns.
Looking Beyond the Credit Score
Specialized programs for credit card consolidation for bad credit prioritize your income stability and current cash flow over a three-digit credit score. They want to see that you have a steady foundation to support a management plan. We use insider knowledge to identify which lenders are most willing to lower interest rates and waive accumulated penalties. This protective expertise helps you avoid the common pitfalls of the debt industry. Whatever you do, don’t take out new payday loans as a temporary fix to pay off credit cards. This only deepens the predatory cycle and complicates your eventual recovery.
Preparing Your Financial Documentation
Organization is your greatest weapon against high-interest debt. You’ll need your most recent billing statements, proof of steady income, and a comprehensive list of all your creditors. Once you have these, you can organize your debt by interest rate to see exactly where your money is going. Whether you prefer the “Avalanche” method of targeting high rates first or the “Snowball” method for early momentum, having a structure is what matters. Bad credit is a temporary financial state, not a permanent part of your identity. You can take the first step toward a debt-free life by choosing a professional debt management service that acts as your dedicated ally.
Strategic Consolidation: Merging Credit Cards and Payday Loans
Many people struggling with debt find themselves fighting a dual-front war. They have maxed-out credit cards and a handful of payday loans they took out just to cover the monthly minimums. This is a compounding trap. Traditional financial advice often fails here because it treats these debts as separate issues. In reality, credit card and payday loan consolidation is the most effective exit strategy for 2026. You cannot effectively pay down a 25% APR credit card balance when a 400% APR payday loan is draining your bank account every two weeks. By merging these obligations, you stop the bleeding and focus your resources on a single, sustainable path toward recovery.
We act as the stable anchor for individuals facing this specific type of financial turbulence. While credit cards represent high-interest unsecured debt, payday loans are predatory instruments designed to keep you in a cycle of borrowing. Effective credit card consolidation for bad credit must address both. If you only fix the cards but leave the payday loans active, the high-cost fees will eventually force you back into using your credit cards for daily expenses. A unified management plan ensures that every dollar you pay actually goes toward reducing your total principal balance.
Stopping the Payday Loan Cycle
Payday loans are designed to be rolled over. Lenders profit from the continuous fees, not the repayment of the principal. This is why payday loan consolidation is essential to your success. It frees up the immediate cash flow you need to make your credit card payments manageable. You also have the legal right to stop ACH withdrawals from your bank account. This is a critical step in regaining control of your income. Once you stop the automatic draining of your funds, you can redirect those dollars toward a managed plan. We handle the aggressive tactics of these lenders so you can focus on your recovery.
Your First Steps Toward Financial Peace
Bankruptcy is often presented as the only way out, but it should always be a last resort. It leaves a long-lasting scar on your financial record. A proactive credit card consolidation for bad credit plan is a much stronger first step. It allows you to honor your obligations while protecting your future agency. At Solid Ground Financial, we’ve been operating since 2004. We use our insider knowledge to negotiate terms that banks simply won’t offer to the general public. You deserve a partner who is tough on the systemic problem but compassionate toward your situation. Get a free debt consolidation quote today and see how much you can save.
Reclaiming Your Financial Agency in 2026
The journey toward a debt-free life begins with the realization that your credit score doesn’t define your future potential. You’ve explored how credit card consolidation for bad credit acts as a strategic shield against predatory lending cycles and compounding interest. By merging high-interest balances with payday loans into a single, manageable payment, you stop the cycle of late fees and regain control over your monthly cash flow. This isn’t just about paying off balances; it’s about securing psychological peace and a clear end date for your financial obligations.
Since 2004, Solid Ground Financial has provided specialized advocacy and A+ rated support for individuals facing intense financial turbulence. We leverage over 20 years of experience to negotiate terms that protect your interests and simplify your path to recovery. You don’t have to face the complexities of the debt industry alone. Take the first step toward financial relief with a free consolidation quote today. Your recovery is possible, and a stable financial future is within your reach.
Frequently Asked Questions
Can I get a debt consolidation loan with a 500 credit score?
Obtaining a traditional personal loan with a 500 score is extremely difficult because most lenders require a minimum of 580. However, credit card consolidation for bad credit is still possible through a debt management plan. These programs don’t rely on your credit score for qualification. Instead, they focus on your ability to make a single, consistent payment. This allows you to lower interest rates without needing a bank’s approval for a new loan.
Will credit card consolidation close my accounts?
If you choose a debt management program, creditors typically require that you close the accounts included in the plan. This is a protective measure to ensure you don’t accumulate new high-interest debt while paying down the old balances. If you use a personal loan for consolidation, you aren’t legally required to close your cards. We often advise keeping them open but inactive to maintain your credit age and improve your utilization ratio over time.
What is the difference between debt consolidation and debt settlement?
Debt consolidation involves merging multiple balances into one payment at a lower interest rate, with the intent to pay the full principal. Debt settlement is different; it involves negotiating with creditors to accept a lump sum that is less than what you actually owe. While settlement might seem faster, it often causes severe, long-term damage to your credit score. Consolidation is a more stable path that focuses on management rather than default.
How much does credit card consolidation usually cost?
The cost depends on the method you choose. For a debt management plan, industry standards typically include a one-time setup fee and a modest monthly administrative fee. These fees are often capped at the state level to protect consumers. If you secure a personal loan, you might face an origination fee, which can range up to 12 percent of the loan amount. We focus on ensuring your total savings from lower interest rates far outweigh these costs.
Can I still use my credit cards after I consolidate them?
You generally cannot use the specific credit cards that are included in a consolidation or management plan. Most creditors will lock or close these accounts as part of the agreement to lower your interest rates. However, you may be able to keep one card outside the plan for emergencies. The goal of credit card consolidation for bad credit is to break the reliance on revolving debt so you can finally achieve a zero balance.
Is debt consolidation better than filing for bankruptcy?
Bankruptcy is a legal process that should only be considered as a last resort because it remains on your credit report for up to ten years. Consolidation is a proactive management strategy that allows you to repay your debts while preserving your financial reputation. It provides a structured path to recovery without the severe legal consequences of a court filing. Choosing consolidation demonstrates a commitment to resolving your obligations and helps you rebuild your credit faster.
How long does the consolidation process take to start?
You can often receive a free debt evaluation and a consolidation quote within minutes of providing your information. Once you agree to a plan, it typically takes one to two billing cycles for your creditors to update their systems with the new, lower interest rates. During this transition, we guide you through every step to ensure your payments are distributed correctly. You’ll see the impact on your monthly cash flow almost immediately.
Will consolidation stop creditors from calling me?
Yes, a structured consolidation plan is one of the most effective ways to stop collection calls. Once your creditors accept the proposal and start receiving regular payments through the program, the harassment generally ceases. We act as your professional advocate, handling the communication with lenders so you don’t have to. This shift from constant stress to a predictable, managed environment is often the biggest relief our clients experience during their recovery.