The math of a payday loan is designed to remain invisible until it’s too late. You’re likely exhausted from the constant anxiety of ACH withdrawals hitting your account before you can even cover your basic living expenses. Understanding the specific payday loan consolidation calculator benefits can help you strip away the lender’s smoke and mirrors to see your debt for what it truly is. It’s common to feel paralyzed by high-interest rollovers where the average APR reaches a staggering 391 percent. We understand the weight of this burden and the specific tactics lenders use to keep you trapped in a cycle of borrowing.
This specialized tool acts as a diagnostic instrument, revealing hidden costs and providing a clear roadmap toward a definitive end date for your debt. We’ll show you how to transition from reacting to financial emergencies to executing a structured recovery strategy. By the end of this article, you’ll learn how to replace multiple high-cost obligations with a single, lower monthly payment. Our goal is to help you regain your personal agency and finally secure the psychological peace of mind you’ve been searching for.
Key Takeaways
- Uncover the mechanics of the payday loan trap and see how high interest rates turn small debts into long-term burdens.
- Identify the essential data points needed to calculate your true cost of debt and compare it against a consolidated repayment plan.
- Explore the primary payday loan consolidation calculator benefits that allow you to visualize a definitive end date for your debt.
- Differentiate between traditional personal loans and relief programs to determine which path fits your current credit profile.
- Learn how to use your calculated results to start a professional consultation and begin the process of lowering your monthly payments.
The Hidden Math of the Payday Loan Cycle
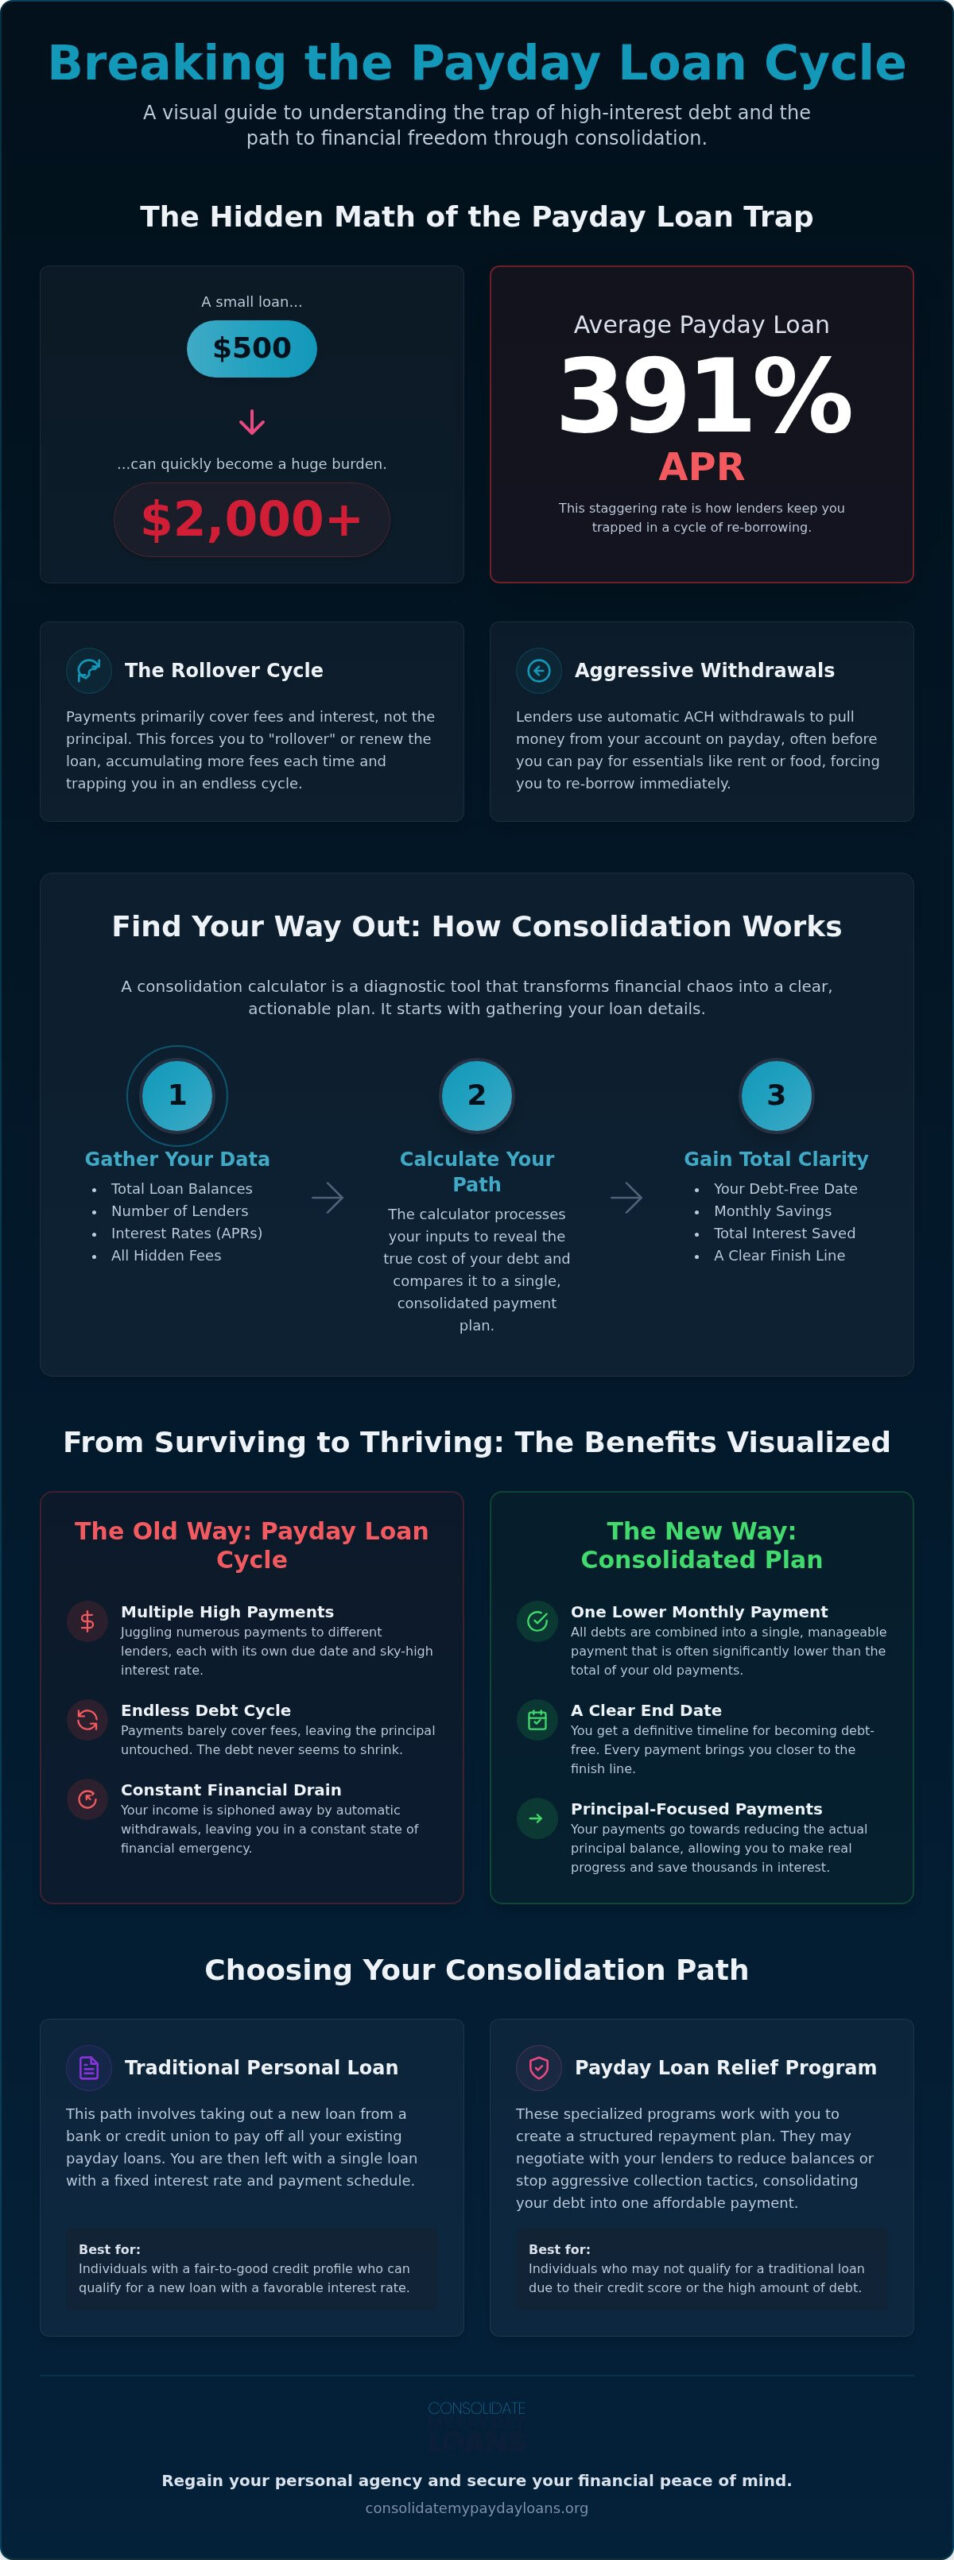
Payday lenders rely on a lack of clarity. They present a $500 loan as a quick fix, but the reality is much darker. With an average interest rate of 391 percent, that small amount can balloon into a $2,000 burden in just a few months. The Hidden Math of the Payday Loan Cycle is built on this exponential growth. Traditional budgeting often fails here because you aren’t just managing expenses; you’re fighting a system designed to outpace your income. Many borrowers experience “math-blindness,” a state of paralysis where the sheer number of high-interest rollovers makes it impossible to see a way out. When you’re juggling multiple lenders, the math stops making sense, and survival mode takes over.
Why Payday Loans Are Designed to Be Infinite
Most people assume their payments are reducing what they owe. In the payday world, that’s rarely true. Lenders prioritize finance charges over principal reduction. This means your hard-earned money only covers the right to keep the debt for another two weeks. Automatic ACH withdrawals reinforce this trap by pulling funds directly from your bank account the moment your paycheck lands. This often leaves you with nothing for rent or groceries, forcing you to borrow again just to survive. Rollover fees are the primary engine of lender profit.
The True Cost of Rollovers and Fees
If you extend a loan three times, the fees can easily exceed the original amount you borrowed. This doesn’t even include the cumulative impact of late fees or non-sufficient funds (NSF) charges if a withdrawal fails. These cascading costs are why understanding payday loan consolidation calculator benefits is so critical. Seeing these numbers in black and white is the first step to financial help for payday loans. It transforms a vague sense of dread into a concrete problem you can solve. A calculator reveals the difference between staying afloat and actually moving forward. You’ll finally see exactly how much of your income is being siphoned away by predatory tactics, giving you the clarity needed to choose a better path.
How a Payday Loan Consolidation Calculator Works
Understanding How a Payday Loan Consolidation Calculator Works is the first step in moving from financial chaos to total clarity. To get an accurate picture of your situation, you’ll need to gather a few essential inputs. These include your total principal balance across all loans, the number of lenders you’re currently paying, and the average interest rates. It’s critical to include all administrative fees and rollover charges in these figures, not just the base interest rate. Many lenders hide the true cost of borrowing in these “extra” fees, which can skew your perception of what you actually owe. By inputting the full data, the tool can calculate the stark difference between making endless ‘minimum payments’ and following a ‘consolidated plan’ with a clear finish line.
One of the most powerful features of this tool is the visualization of your ‘debt-free date’. When you’re stuck in a cycle of high-interest rollovers, the end of the debt often feels like a moving target that’s always out of reach. Seeing a specific month and year on your screen acts as a powerful motivator for change. It transforms a vague hope into a concrete, data-driven goal. This clarity allows you to stop guessing about your future and start planning for it with confidence.
Decoding Your Calculator Results
When you use the payday loan consolidation calculator, the results offer more than just raw numbers. ‘Potential Monthly Savings’ is a direct measure of your daily cash flow. This is the money that stays in your pocket for groceries, rent, or emergency repairs rather than going into a lender’s pocket. One of the primary payday loan consolidation calculator benefits is the ability to see the massive reduction in total interest paid over the life of the debt. You’ll understand exactly how much faster you can reach freedom when your payments actually go toward the principal balance rather than just covering the cost of staying in debt.
The ‘Aha!’ Moment: Identifying Your Break-Even Point
The ‘Aha!’ moment happens when the data reveals your break-even point. This is the moment you recognize that your current payments are only covering interest and fees, leaving the principal untouched month after month. At this stage, consolidation becomes a mathematical necessity rather than just an option. Using these hard numbers to justify the transition to a payday loan relief program removes the emotional weight of the decision. You’re no longer making a choice based on fear; you’re making a strategic move to protect your financial future. You can explore your consolidation options today to see how these numbers apply to your specific situation.
Strategic Benefits of Visualizing Your Consolidation
Visualizing your debt isn’t just about the math; it’s about reclaiming your agency. One of the primary payday loan consolidation calculator benefits is the shift from emotional paralysis to strategic action. Instead of waking up with a vague sense of dread about your bank balance, you gain a data-driven recovery plan. This visualization acts as an “insider” advantage. You finally see exactly what lenders are taking from you in fees alone. Knowledge is your best defense against predatory tactics. When a lender offers “more cash” to cover an existing rollover, your calculator results show you the true cost of that trap. This data acts as a shield, helping you say no to products that would only deepen your struggle.
Consolidating into a single monthly payment frees up significant mental bandwidth. You no longer have to track five different withdrawal dates or wonder which lender will hit your account first. This simplification allows you to focus on your life and family rather than just managing a crisis. It turns a chaotic cycle into a predictable, manageable process.
Psychological Relief Through Data Clarity
Clarity transforms your internal narrative. You move from the overwhelming feeling of “I’m drowning” to the manageable reality of “I have a $2,500 problem with a $200-a-month solution.” Seeing a finite end date on your screen immediately lowers stress levels. It provides a light at the end of the tunnel that was previously invisible. This specific data also makes it easier to talk to a spouse or partner. Instead of hiding the debt out of shame, you can present a clear, actionable plan for recovery. It replaces tension with a shared goal.
Prioritizing the Right High-Interest Targets
The calculator helps you decide where to strike first. In a payday context, traditional methods like the “snowball” (paying the smallest balance) or “avalanche” (paying the highest interest) take on new urgency. You can see exactly how much each day of delay costs you in interest and fees. This “cost of waiting” is often the ultimate catalyst for seeking professional help. By visualizing the cumulative fees over the next six months, the necessity of a structured program becomes undeniable. You stop guessing which debt is the most dangerous and start eliminating them with precision.
Comparing Consolidation Paths: Loan vs. Relief Program
Many financial experts suggest taking out a personal loan to pay off payday debt. While the average personal loan interest rate sits around 12.28 percent, this option is often a myth for those trapped in the payday cycle. High-interest rollovers and constant ACH withdrawals quickly damage your credit score, making it nearly impossible to qualify for traditional bank products. Understanding the specific payday loan consolidation calculator benefits helps you choose between the dream of a new loan and the reality of a relief program. Instead of chasing a loan you can’t get, you should focus on how negotiation works for those with poor credit. These programs don’t rely on your credit score; they rely on structured settlements to resolve what you owe.
When you compare the math, the differences are clear. A consolidation loan replaces one debt with another at a fixed interest rate. A relief program, however, works to lower the actual balance through negotiation. This is particularly effective for payday loans where the interest has already far exceeded the original principal. Seeing these paths side-by-side allows you to make a strategic decision based on your actual financial standing rather than a hypothetical credit score.
When a Traditional Bank Says No
Traditional lenders see payday loan history as a major red flag. When a bank says no, it can feel like you’ve hit a dead end. However, relief programs provide a vital safety net for distressed borrowers; these programs focus on your current ability to make a single payment rather than your past credit mistakes. Choosing a payday loan consolidation partner that understands lender tactics is essential. They know how to navigate the aggressive collections and legal threats that often follow high-cost debt, providing a buffer between you and the lender.
The Role of Professional Negotiation
Expert negotiators act as your advocate in a system that’s weighted against you. They work to stop escalating fees and lower your total balance without requiring you to take on a new loan. This intervention often silences lender aggression and stops the cycle of unauthorized bank withdrawals. Professional negotiation fundamentally changes the math of your consolidation calculator results by shifting the focus from paying interest to settling the principal. After seeing your true debt load, a payday loan hardship program might be your most viable path forward. You can request a professional review of your options today to see which path fits your specific needs.
From Calculation to Action: Starting Your Relief Plan
Once the calculator reveals the true cost of your debt, the focus must shift to execution. Interpreting your results during a professional consultation is quite different than just looking at a screen. A specialist helps you validate those numbers and maps them directly to your actual household budget. You’ll move from “seeing the savings” to “securing the savings” by identifying which lenders are the most aggressive and which balances need immediate intervention. This transition is where the payday loan consolidation calculator benefits become a tangible reality. You aren’t just looking at theoretical numbers anymore; you’re building a financial barrier between yourself and predatory lending practices.
Preparation is the key to a smooth start. You’ll need to gather your recent bank statements, original loan agreements, and the most current balances for every lender you owe. Having this documentation ready allows your advocate to move quickly and negotiate from a position of strength. The most critical rule of starting any relief plan is simple: you must stop the borrowing cycle the moment you begin. Taking out a new loan while in a consolidation program is like trying to bail out a boat while someone else is drilling holes in the bottom. It undermines the negotiation process and can completely reset your progress toward freedom.
Customizing Your Consolidation Strategy
A “one size fits all” calculation is a helpful starting point, but it needs a human expert to refine it. Your actual monthly take-home pay might fluctuate, or you might have other obligations that the digital tool doesn’t account for. A customized strategy ensures your new payment is actually sustainable for the long haul. Many borrowers find that credit card and payday loan consolidation provides a more unified exit strategy. By addressing all high-interest debt at once, you simplify your financial life and maximize your available monthly cash flow.
Taking the First Step Toward Financial Peace
Expect some pushback from your lenders when you start a consolidation program. They’ve relied on your rollovers for consistent income and won’t let go of that revenue without a fight. Your consolidation partner handles these communications, acting as a protective buffer against aggressive collection calls. Understanding the full scope of payday loan consolidation calculator benefits gives you the confidence to stand your ground when lenders try to lure you back into another rollover. On “day one” of your new plan, you’ll experience a profound sense of relief. The constant fear of unauthorized bank withdrawals stops, and you finally have a predictable schedule. You can estimate your path to debt relief and speak with a specialist today to start your recovery.
Reclaiming Your Financial Agency Today
You don’t have to live in a state of constant anxiety over ACH withdrawals and predatory interest rates. By understanding the specific payday loan consolidation calculator benefits, you’ve already taken the most difficult step: facing the data. We’ve explored how specialized tools reveal the hidden math of the lending cycle and why a structured relief program often succeeds where traditional bank loans fail. You now have the clarity to see that your debt is a solvable problem with a definitive end date. It’s no longer an invisible trap; it’s a manageable challenge with a clear exit strategy.
Our debt specialists provide non-judgmental support and expert negotiation to stop predatory fees, replacing your stress with a single manageable monthly payment. It’s time to stop reacting to financial emergencies and start executing your recovery plan. Estimate Your Savings and Start Your Relief Plan Now to regain control of your bank account and your peace of mind. You’ve seen the numbers; now it’s time to secure the savings and move toward a future free from the payday loan cycle. Your path to financial stability starts with a single, data-driven decision.
Frequently Asked Questions
How much can I save with a payday loan consolidation calculator?
Your potential savings depend on your total balance and the average interest rates of your current lenders. By entering your specific debt details, the tool estimates how much you could save by stopping the cycle of 391 percent APR rollovers. It calculates the difference between paying only interest fees and following a structured plan where your payments actually reduce the principal. This clarity helps you see the tangible financial impact of choosing a relief program over a lender extension.
Will using a consolidation calculator affect my credit score?
No, using a calculator is a private planning step that does not involve a credit inquiry. It is a risk-free way to explore your options and understand the payday loan consolidation calculator benefits without alerting lenders or credit bureaus. Your credit score is only impacted if you later choose a specific relief path that involves debt settlement or closing accounts. At this initial stage, the tool is strictly for your own data-driven visualization and recovery planning.
Can I consolidate my payday loans if I have very bad credit?
Yes, you can absolutely consolidate your debt even with a poor credit history. Unlike traditional bank loans that require high scores, payday loan relief programs are designed for individuals who are already in financial distress. These programs focus on your current income and your ability to make a single, manageable payment rather than your past credit mistakes. We act as a stable anchor, helping you navigate the recovery process regardless of your current credit standing.
What is the difference between a debt consolidation loan and a relief program?
A consolidation loan is a new credit product used to pay off old balances, which usually requires a credit score above 670. In contrast, a relief program uses professional negotiation to restructure your existing debt without a new loan. Relief programs are often the only viable path for payday borrowers because they stop the cycle of predatory fees directly. This approach focuses on settling the debt for less than you owe rather than just moving the balance elsewhere.
How do I know if the calculator results are accurate for my specific loans?
The accuracy of the results depends entirely on the data you provide. You should include your total principal, any accrued late fees, and the specific finance charges found in your original loan agreements. While the calculator provides a reliable estimate based on industry averages, a professional consultation is needed to verify the exact tactics of your specific lenders. A specialist can refine the calculation to account for the nuances of different high-interest obligations and lender behaviors.
Can I include credit card debt in my payday loan consolidation calculation?
Yes, you can include credit card balances in your total calculation to create a unified exit strategy. Combining all unsecured debt into one plan simplifies your monthly finances and prevents high-interest credit cards from undermining the progress you make on your payday loans. This holistic view of your debt is essential for reclaiming your mental bandwidth. It allows you to manage all your obligations through a single, structured payment plan that fits your household budget.
What happens if my calculator shows I can’t afford the consolidated payment?
If the estimate appears too high, it’s a clear signal that you need the professional negotiation found in a relief program. One of the primary payday loan consolidation calculator benefits is identifying when a simple payment plan isn’t enough to solve the problem. In these cases, specialists work to negotiate deeper settlements or longer terms to bring the payment within your reach. This data ensures you don’t commit to a plan that is doomed to fail from the start.
Is there a fee to use a payday loan consolidation calculator?
No, the calculator is a free resource provided to help you visualize your path to financial help. We believe in providing transparency so you can understand the true cost of your debt before making any commitments. Fees only apply if you decide to enroll in a managed consolidation or relief program where we handle the lender negotiations on your behalf. Our revenue comes from managing the recovery process, not from providing the initial diagnostic tools you need to get started.