What if the $1.26 trillion in credit card debt currently weighing down American households isn’t actually your biggest financial threat? While the average credit card interest rate has climbed to 19.35% as of August 2026, it’s the predatory payday loans with APRs exceeding 400% that often trigger a total financial collapse. It feels like you’re pouring water into a bucket full of holes; no matter how much you pay, the balance never seems to drop. You’re likely exhausted by aggressive bank withdrawals and the anxiety of constant collection calls. We understand that this cycle feels impossible to break, but it’s often more effective to consolidate payday loans and credit card debt into a single, unified strategy rather than fighting them as separate battles.
You deserve a clear path back to financial stability and psychological peace. By merging these high-interest obligations into one manageable plan, you can finally stop the automatic bank withdrawals that leave your account empty every payday. This guide will show you how to secure a single monthly due date and significantly reduced interest rates, even if your credit score has taken a hit. We’ll walk through the mechanics of debt relief and provide a clear timeline for when you’ll be entirely debt-free. It’s time to reclaim your agency and move toward a future where your money finally stays in your own pocket.
Key Takeaways
- Identify the mechanics of the “Dual Debt Trap” and understand how payday loan rollovers systematically drain the cash flow needed to pay down credit card principal.
- Discover the most effective ways to consolidate payday loans and credit card debt into a single, unified management plan that simplifies your monthly obligations.
- Evaluate the critical differences between traditional personal loans and specialized relief programs to choose the path that best fits your credit profile and budget.
- Learn how to use a specialized consolidation calculator to estimate your potential savings and see a clear timeline for your recovery.
- Follow a structured five-step inventory and action plan to stop predatory bank withdrawals and regain total agency over your financial future.
The Dual Debt Trap: Why Payday Loans and Credit Cards Create a Cycle
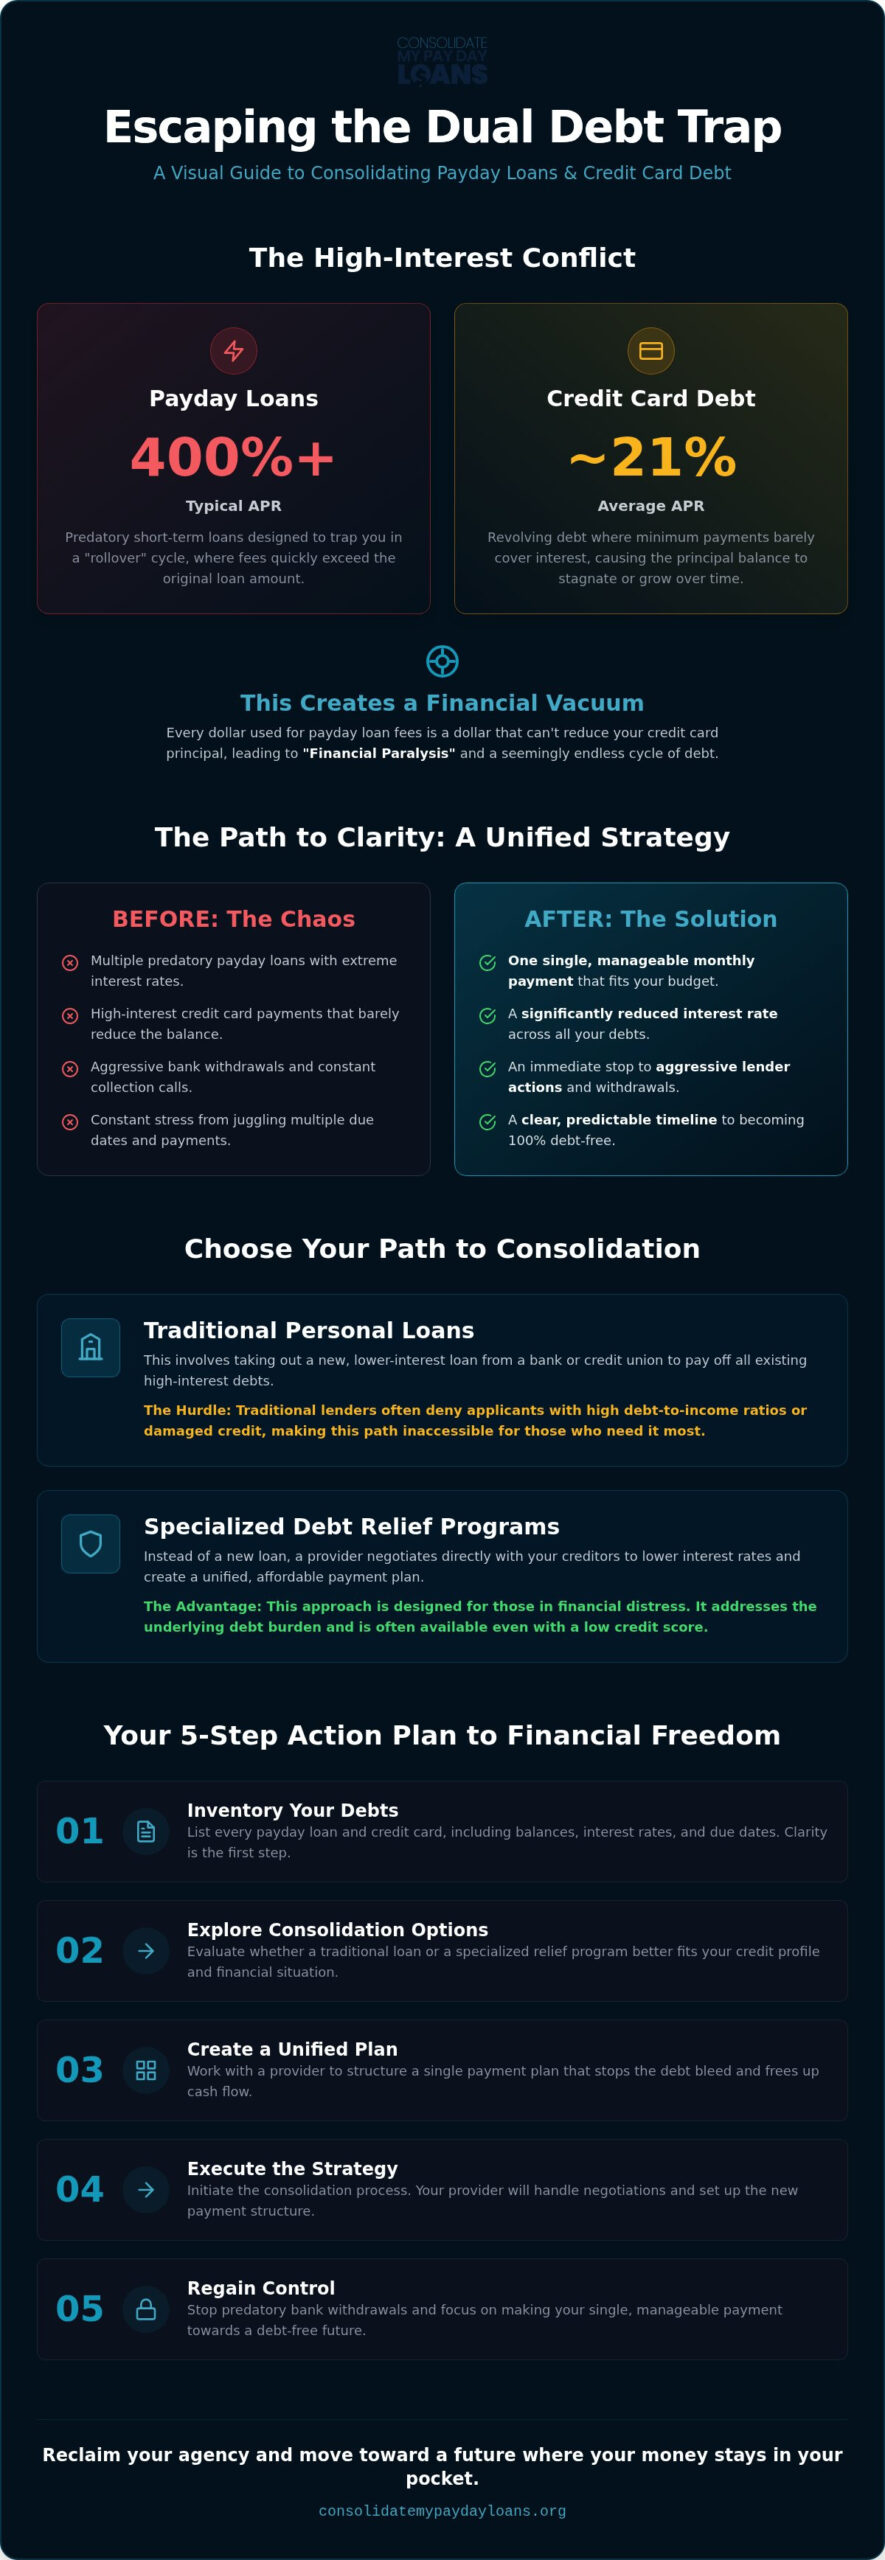
The “Dual Debt Trap” isn’t just a financial term; it’s a suffocating reality for millions of Americans. It happens at the intersection of revolving credit card debt and high-velocity payday loans. While credit cards allow for minimum payments that barely touch the principal, payday loans demand immediate, full repayment within weeks. This conflict creates a financial vacuum. Every dollar you spend on a payday loan rollover is a dollar you can’t use to pay down your credit card principal. The result is a credit card balance that never drops and a payday loan that keeps ballooning.
Managing this conflict is mentally and emotionally exhausting. You’re forced to track multiple due dates while facing aggressive collection tactics that don’t respect your peace of mind. This constant state of alert leads to “financial paralysis,” where you’re so busy putting out fires that you can’t plan for the future. Debt consolidation is the process of simplifying multiple high-interest obligations into one payment to end this chaos and restore your sanity.
The Math Behind the Cycle: APRs and Rollovers
The numbers reveal why this cycle is so difficult to break without help. As of August 2026, the average credit card interest rate sits at 19.35%, with the Federal Reserve reporting averages as high as 21.15% for some accounts. While these rates are high, they pale in comparison to payday loans, which frequently carry APRs exceeding 400%. The “rollover effect” is the most dangerous part of this equation. It’s a trap where fees exceed the original loan amount in just a few weeks. You quickly find yourself robbing Peter to pay Paul, taking out a new high-interest loan just to cover the interest on the previous one.
Why Traditional Banks Often Say No
When you try to consolidate payday loans and credit card debt through a traditional bank, you’ll likely hit a wall. High debt-to-income ratios and damaged credit scores make you look like a high risk to big lenders. Traditional banks often focus on your FICO score, which might not even show your payday loan history. These loans are often invisible to standard credit reports, but specialized lenders and relief providers know exactly how to find them. This visibility gap is why standard personal loans often fail those in deep distress. You need a specialized approach that recognizes the unique burden of payday lending to finally break free.
How to Consolidate Payday Loans and Credit Card Debt Together
Breaking the cycle of high-interest debt requires more than just making larger payments. It requires a unified exit strategy for 2026 that looks at your total financial picture. When you decide to consolidate payday loans and credit card debt, you’re not just moving numbers around on a spreadsheet. You’re creating a protective barrier between your bank account and predatory lenders. A specialized provider can group these disparate obligations into one structured plan, allowing a debt counselor to evaluate your debt-to-income ratio and negotiate terms that actually fit your current reality.
Success in financial recovery depends heavily on cash flow management. It’s a common mistake to focus only on interest rates. While lowering a 400% APR is vital, the immediate goal is ensuring you have enough money left for rent and groceries after your debt payment. Consolidation provides the breathing room necessary to stop the “debt bleed” and begin building a stable foundation.
Consolidation Loans vs. Debt Relief Programs
Traditional consolidation loans involve taking out a new personal loan to pay off your current creditors. This can be effective if you have a decent credit score, but many trapped in the payday cycle don’t qualify for competitive rates. The Consumer Financial Protection Bureau guide to debt consolidation highlights that while loans can simplify payments, they don’t always address the underlying debt burden. This is where debt relief programs differ. Instead of a new loan, these programs negotiate directly with lenders to lower your total payments. This path is often more realistic for those dealing with aggressive payday lenders who refuse to work with traditional banks.
The Mechanics of a Unified Payment
Once you enter a unified plan, the complexity of your financial life drops instantly. You make one monthly payment to a dedicated account, and those funds are distributed to your various creditors on your behalf. This system provides several key benefits:
- Fixed monthly payments that never fluctuate unexpectedly, making budgeting simple.
- A documented end date when you’ll be 100% debt-free, providing a light at the end of the tunnel.
- An end to the stress of managing multiple manual transfers and tracking a dozen different due dates.
Taking this step allows you to stop reacting to financial crises and start following a roadmap. If you’re ready to see how this approach works for your specific balances, you can explore our relief options today and start the process of regaining control.
Choosing Your Path: Personal Loans vs. Specialized Relief
Deciding how to consolidate payday loans and credit card debt depends heavily on your current credit standing and immediate cash flow needs. While both paths aim to simplify your finances, they operate on completely different mechanics. A new loan replaces old debt with a single interest rate, while a relief program restructures your existing obligations through negotiation. Understanding which framework fits your situation is the first step toward regaining your agency. You should evaluate your debt consolidation options carefully to avoid falling into another high-interest trap.
The impact on your monthly budget is the most tangible difference between these two choices. A personal loan offers a fixed monthly payment, but a relief program can often reduce that monthly payment even further by negotiating the principal or interest. Payday rollovers are designed to be invisible costs that keep you paying forever. In contrast, a consolidation service uses transparent, structured fees that lead to a confirmed debt-free date. This clarity replaces the anxiety of the unknown with a predictable roadmap for recovery.
When a Personal Loan Makes Sense
If your credit score is above 660 and you have a stable income, a personal loan might be your best tool. As of June 2026, the average personal loan interest rate is 12.28%, which is significantly lower than the 19.35% average for credit cards. This immediate payoff of creditors stops the interest bleed instantly. However, it requires discipline. If you don’t address the habits that led to the debt, you risk running up your credit card balances again while still owing the new loan. It’s a solution for those who have the credit strength to qualify but need a lower interest rate to accelerate their progress.
When a Specialized Relief Program is Superior
For those with credit scores below 600, multiple payday loans, or “unbankable” status, traditional banks often prove inaccessible. This is where payday loan relief becomes a superior alternative. These programs don’t typically rely on a credit check for qualification. Instead, they focus on stopping aggressive bank withdrawals and negotiating lower balances through professional advocacy. While you may need to close the credit card accounts included in the program, the benefit is a structured path to freedom without the hidden costs of constant rollovers. It’s a protective shield for those the traditional banking system has left behind.
5 Steps to Consolidate Your Payday and Credit Card Debt Today
Taking the first step toward financial recovery requires a shift from reactive panic to proactive planning. You can’t fix what you haven’t measured. Your first priority is to inventory every lender, current balance, and upcoming due date to see the full scope of your obligations. Once you have these numbers, use a payday loan consolidation calculator to estimate your potential savings. This tool helps you visualize how much of your hard earned money is currently being wasted on interest versus how quickly you could reach zero with a structured plan.
The path to consolidate payday loans and credit card debt becomes much clearer once you stop the immediate “debt bleed.” After you’ve run the numbers, you must regain control of your bank account. This involves a specific legal process to stop lenders from draining your funds before you can pay for essentials like housing or food. Finally, you’ll consult with a specialized advocate to review your relief options and enroll in a single payment plan that fits your actual monthly budget.
Regaining Control: Revoking ACH Authorization
You have a legal right to stop automatic withdrawals from your bank account. To do this, you must notify the lender in writing that you are revoking their authorization to debit your account. Simultaneously, you should notify your bank. Most financial institutions allow you to place a “Stop Payment” order on specific recurring transfers. It’s vital to remember that revoking ACH authorization does not cancel the debt itself. It simply stops the “account emptying” cycle that often leads to overdraft fees and financial instability. This step gives you the breathing room needed to negotiate a fair settlement or consolidation plan.
Working with a Consolidation Advocate
A specialized advocate acts as your protective shield against aggressive collection tactics. During your initial consultation, they’ll perform a deep income review and debt analysis to ensure the proposed plan is sustainable. These experts use their insider knowledge of lender tactics to negotiate for waived late fees or significantly lower interest rates. They understand how to handle the high velocity of payday lenders while balancing your credit card obligations. Honesty is your best tool here. By disclosing all debts, you allow the advocate to create a comprehensive strategy that addresses every leak in your bucket. If you’re ready to stop the cycle, you can start with a professional debt evaluation to see which relief path is right for you.
Once your plan is active, your only job is to stick to the single payment schedule. This consistency is what ultimately breaks the cycle. By replacing a dozen chaotic due dates with one predictable monthly transfer, you regain your psychological peace and your financial agency.
Regaining Financial Agency with Consolidate My Payday Loans
Financial turbulence doesn’t have to be your permanent reality. Regaining your agency starts with admitting that the current high-interest system is designed to keep you trapped in a cycle of perpetual repayment. Consolidate My Payday Loans acts as a dedicated ally against the complex traps of the predatory lending industry. We specialize in helping individuals who feel like they’re paying every week, yet the balance never drops. Our payday loan hardship program isn’t a temporary band-aid. It is a comprehensive, structured methodology designed to stop the cycle of rollovers and high fees for good. We speak directly to your stress with calm reassurance, offering a supportive environment where your financial past is never judged.
When you choose to consolidate payday loans and credit card debt, you’re choosing a path that prioritizes your psychological peace and tangible financial improvement. The goal is to move you from a state of constant alert to a state of stable, predictable peace. We understand the weight of aggressive collection calls and the fear of empty bank accounts. Our approach is designed to restore your personal agency, giving you back control over your income and your future. You aren’t just a file number to us; you’re a partner in recovery.
Why Specialized Experience Matters
Specialized experience is the critical difference between a failed attempt and a successful recovery. Solid Ground Financial has operated as a stable anchor for consumers since 2004, giving us over two decades of experience managing the most complex high-interest obligations. When you consolidate payday loans and credit card debt with us, you benefit from counselors who understand the nuances of various debt types. We have the “insider knowledge” of how payday lenders operate and where they are likely to negotiate. This perspective turns a one-sided struggle into a professional, fair negotiation. Our focus remains on your long-term financial health, ensuring you have the tools to stay debt-free long after the program ends.
Your First Step Toward Relief
You can begin your recovery today without any immediate pressure or obligation. We invite you to use our specialized online savings calculator as a low-pressure entry point to see what’s possible for your specific situation. It provides a clear, data-driven view of your potential savings and a projected date for when you will be entirely debt-free. The enrollment process is methodical and highly organized, designed to build your confidence from the very first interaction. Once you’re in the program, the immediate relief of a single payment replaces the chaos of multiple, high-velocity due dates. You don’t have to face aggressive lenders alone. Our team is here to act as your protective expert, leading you toward a safer and more manageable financial future.
Reclaiming Your Financial Future in 2026
You’ve seen how the cycle of high-interest debt is designed to keep you in a state of constant survival. By revoking ACH authorizations and moving toward a unified management plan, you can stop the “debt bleed” that drains your bank account every week. Whether you choose a personal loan or a specialized relief program, the ultimate goal is regaining your agency. It’s entirely possible to consolidate payday loans and credit card debt into a single, manageable path that leads to a confirmed debt-free date. This structure replaces financial chaos with a predictable roadmap for recovery.
Operated by Solid Ground Financial since 2004, our team provides A+ rated empathetic financial advocacy through specialized payday loan relief programs. We understand the mechanics of predatory lending and have the “insider knowledge” needed to negotiate on your behalf. You don’t have to navigate these complex tactics alone. Take the first step toward psychological peace and financial stability right now. Calculate Your Savings and Start Your Consolidation Plan Today. Your recovery starts with a single decision to prioritize your future over your past.
Frequently Asked Questions
Can I consolidate payday loans and credit cards with bad credit?
Yes, you can consolidate payday loans and credit card debt even with a credit score below 600. Traditional banks often reject borrowers with high debt-to-income ratios, but specialized relief programs focus on your ability to pay rather than your FICO score. These programs prioritize stopping the cycle of predatory rollovers. By evaluating your actual monthly income, advocates can structure a plan that fits your budget regardless of past credit challenges.
How does payday loan consolidation affect my credit score?
Consolidation typically has a mixed impact on your credit score. You might see an initial dip if you close credit card accounts included in the program, as this affects your credit utilization and account age. However, your score often improves over time as your total debt decreases and you eliminate the risk of missed payments. Replacing chaotic, high-interest balances with a structured payment plan is a proven way to rebuild long-term financial health.
Will consolidation stop payday lenders from calling me?
Yes, a professional consolidation program is designed to stop the harassment from collection agencies. Once you enroll, your advocates begin communicating directly with your lenders on your behalf. They use established legal frameworks to redirect collection efforts away from your personal phone and workplace. This intervention provides the psychological peace needed to focus on your recovery. It’s one of the most immediate benefits of moving into a managed debt relief plan.
Do I need to take out a new loan to consolidate my debt?
No, you don’t necessarily need a new loan to consolidate payday loans and credit card debt. While some people use personal loans for this purpose, specialized relief programs focus on negotiating with your current lenders to lower interest rates and waive fees. This approach is often safer for those who can’t qualify for competitive bank rates. It allows you to pay off your existing balances through a single monthly payment without adding a new interest-bearing contract.
What happens if I can’t afford the new consolidated payment?
Relief plans are specifically built around your verified income to ensure they are sustainable. If your financial situation changes unexpectedly, it’s vital to contact your counselor immediately. Because these programs are structured to help you succeed, counselors can often review your budget and work with lenders to adjust the terms. The goal is to keep you on the path to being debt-free while ensuring your basic needs, like housing and food, are always met.
How long does the consolidation process typically take?
The initial setup and enrollment process often take just a few days to a couple of weeks. However, the journey to becoming completely debt-free typically lasts between 12 and 48 months. The exact duration depends on the total amount you owe and the specific terms negotiated with your lenders. You’ll receive a clear, documented end date at the start of your program so you can track your progress toward total financial freedom.
Can I include all my credit cards in a payday loan relief program?
Most unsecured credit card balances can be included in a comprehensive relief program. During your initial consultation, an advocate will review your total debt inventory to determine which accounts are eligible for negotiation. While you might choose to keep one card for emergencies, including all high-interest accounts usually results in the most significant monthly savings. This unified approach ensures that all your predatory debt is managed under a single, simplified strategy.
Is revoking ACH authorization legal for payday loans?
Yes, revoking ACH authorization is a legal right protected by federal law. You can stop automatic withdrawals by notifying both your lender and your bank in writing at least three business days before the scheduled transfer. While this doesn’t cancel the debt you owe, it stops lenders from emptying your account before you can pay for essentials. It’s a critical first step in regaining control of your cash flow and stopping the cycle of overdraft fees.