What if your next paycheck actually stayed in your bank account instead of disappearing into a web of automatic withdrawals the moment it cleared? For many, the reality is an exhausting cycle of 400% APR interest and multiple due dates that lead to constant overdraft fees. If you’re tired of the aggressive collection calls and the pressure to re-borrow every two weeks, you need a proven strategy to consolidate payday loans into one monthly payment and break the predatory lending cycle for good.
We understand that facing these lenders alone feels like an uphill battle against a system designed for you to fail. It’s a heavy burden, but you don’t have to carry it indefinitely. This 2026 guide provides a clear, step-by-step methodology to help you regain control. You’ll learn how to stop the drain on your bank account, negotiate for reduced total interest, and finally merge those scattered obligations into a single, manageable payment that fits your life. It’s time to trade the chaos of debt for the stability of financial peace of mind.
Key Takeaways
- Understand why the “rollover” cycle is designed to keep you in debt and how to effectively disrupt the mechanic where fees exceed your original principal.
- Discover how to consolidate payday loans into one monthly payment through a structured relief program that doesn’t require a new loan or a perfect credit score.
- Learn the critical process of revoking ACH authorizations to regain immediate control of your bank account and stop predatory automatic withdrawals.
- Compare the practical differences between credit-based personal loans and debt management plans to identify the most sustainable path for your recovery.
- Gain actionable strategies for managing your monthly cash flow and building a starter emergency fund once your scattered debts are simplified.
The Payday Loan Debt Trap: Why Multiple Payments Are Designed to Fail
It’s Friday afternoon, and instead of feeling the relief of a finished work week, you’re staring at your banking app with a sense of dread. You aren’t alone in this struggle. Approximately 12 million Americans use these high-interest products every year, often finding themselves caught in a cycle that feels impossible to escape. To understand how to break free, it’s helpful to look at what are payday loans and why their structure is intentionally designed to trigger a cascade of financial failures. When you have three or four lenders all pulling from your account on different days, “just paying the minimum” becomes a mathematical trap rather than a solution.
The stress of managing staggered due dates is overwhelming. One lender hits your account on the 1st, another on the 5th, and a third on the 15th. This constant activity makes it nearly impossible to keep track of your actual balance, leading to bank overdrafts and aggressive collection calls. These lenders count on this chaos. They know that when you’re overwhelmed, you’re more likely to accept a “rollover” just to stop the immediate pressure. However, this only deepens the hole. If you want to regain control, the most effective path is to consolidate payday loans into one monthly payment, which replaces the scattered panic with a singular, predictable obligation.
The Math of the Debt Spiral
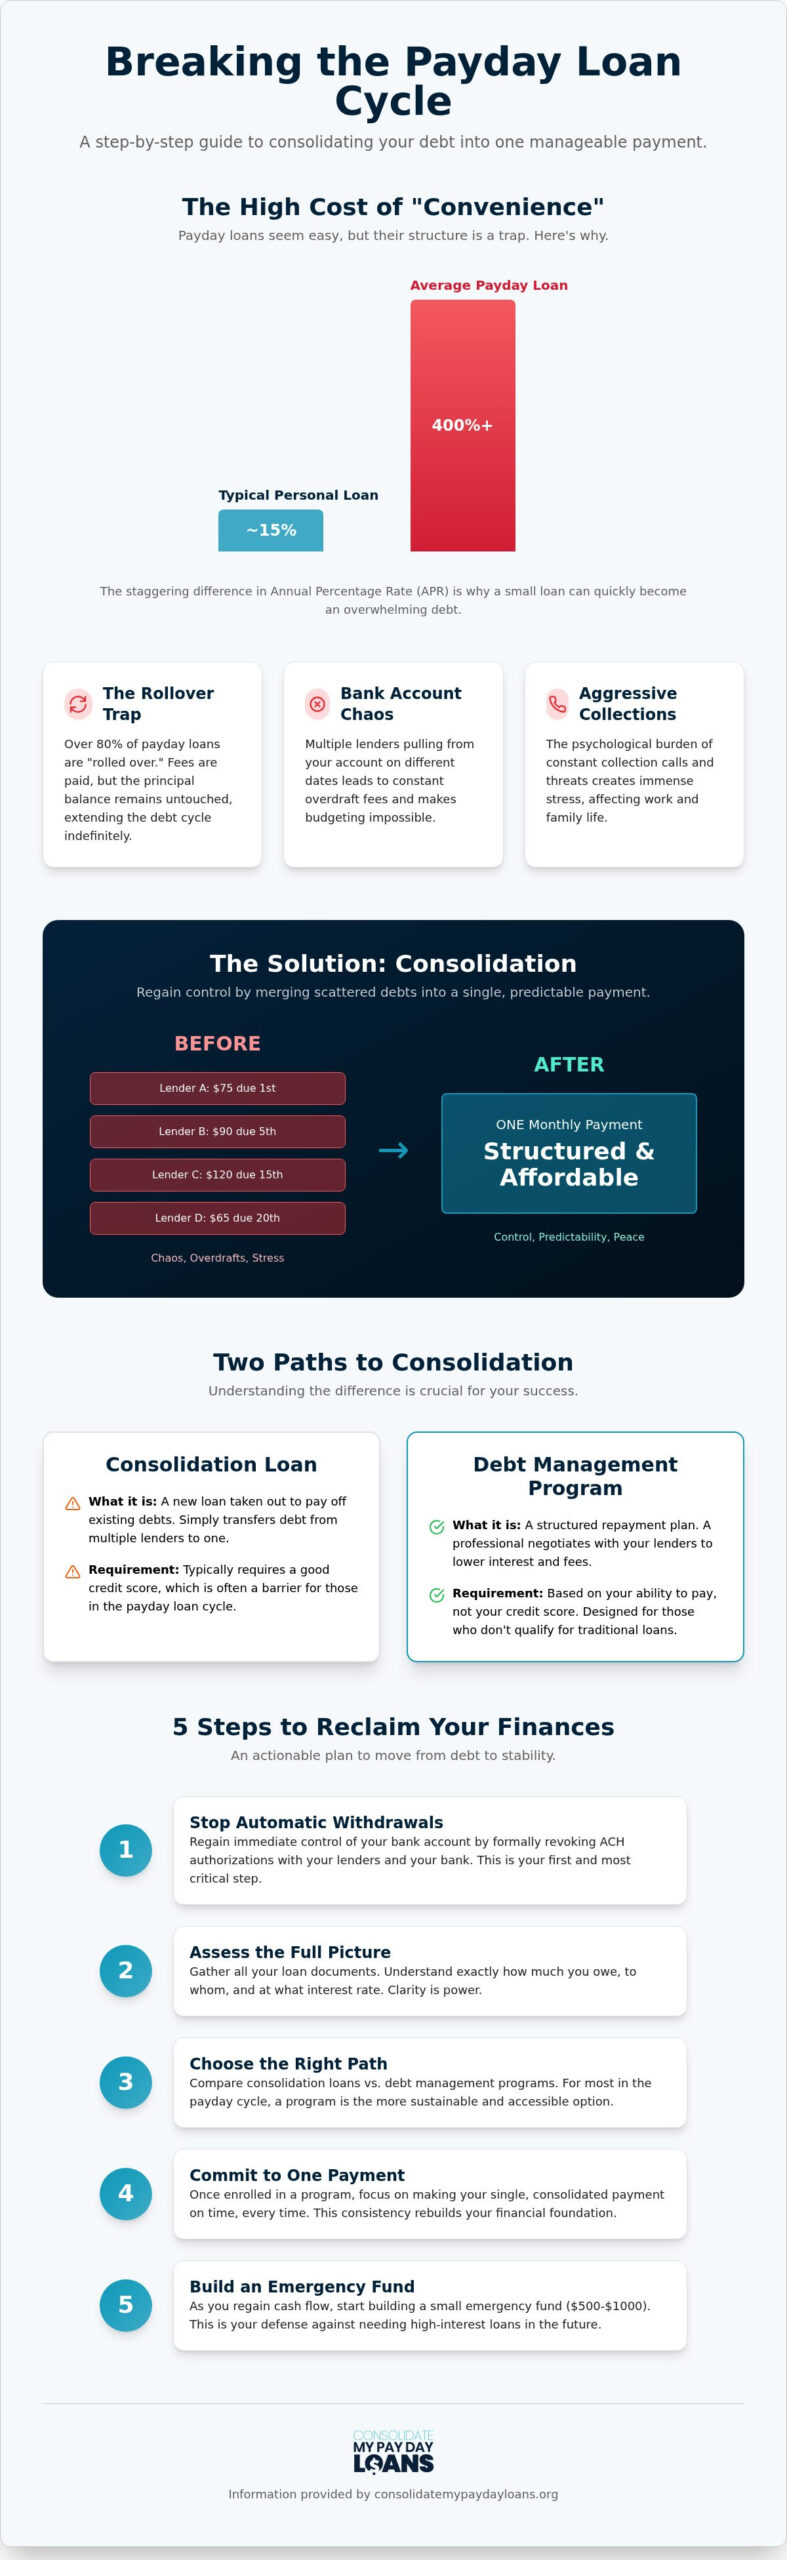
The numbers behind these loans are staggering. While a typical personal loan in 2026 might carry an interest rate around 13% to 15%, payday loans frequently exceed 400% APR. This difference is the reason a small $500 cash advance can balloon into a $2,000 burden in just a few months. When you pay a “rollover fee” of $75 to extend a $500 loan, that money doesn’t reduce your balance by a single cent. It only buys you two more weeks of time.
Most borrowers eventually fall into the re-borrowing phenomenon. You pay off one loan only to find you no longer have enough money for rent or utilities, forcing you to take out a new loan immediately. It isn’t a lack of discipline; it’s the natural result of triple-digit interest rates draining your liquidity. This cycle ensures that your paycheck is spoken for before you even receive it.
The Psychological Burden of Predatory Lending
Living under the weight of predatory debt is exhausting. The constant anxiety of bank alerts and the fear of your phone ringing can affect your performance at work and your relationships at home. It feels like you’ve lost agency over your own life. Choosing to consolidate payday loans into one monthly payment acts as a stable anchor in this turbulence. By merging these debts, you stop the multiple automatic withdrawals that keep your bank account in the red. This shift doesn’t just manage your money; it restores your peace of mind and allows you to look toward a future where your income actually belongs to you.
Understanding Consolidation: Merging Debt Without a New Loan
Many people assume that to consolidate payday loans into one monthly payment, you must first qualify for a traditional bank loan. That isn’t always the case. In fact, for those already caught in the payday loan debt trap, where the CFPB reports over 80% of loans are rolled over within two weeks, qualifying for new credit is often impossible. Payday loan consolidation is better understood as a management process rather than a specific financial product. It focuses on restructuring your existing obligations into a single, manageable stream without requiring a high credit score or a new lender to approve you.
It’s vital to distinguish between a consolidation loan and a consolidation program. A loan involves borrowing new money to pay off old lenders, which simply moves the debt from one place to another. A program, however, involves a professional advocate negotiating directly with your current lenders to lower interest rates and stop predatory fees. This distinction is crucial for anyone whose credit has been bruised by the very cycle they’re trying to escape. By choosing a program, you can consolidate payday loans into one monthly payment based on what you can actually afford, not what a high-interest contract demands.
How a Consolidation Program Works
When you enter a relief-based program, your various lenders are grouped into one organized repayment schedule. Instead of juggling five different due dates and risking multiple overdraft fees, you make a single payment to a management company. They then handle the distribution of funds to your lenders according to a pre-negotiated plan. During this process, interest and fees are often frozen or significantly reduced. This ensures that every dollar you pay actually goes toward reducing your principal balance rather than just covering another rollover fee.
The Role of the Professional Advocate
You don’t have to face aggressive lenders alone. A professional advocate, like Consolidate My Payday Loans, acts as an “insider” ally who understands the industry’s tactics and legal requirements. They handle the difficult negotiation process that stops the cycle of endless rollovers and puts an end to direct lender harassment. This protection provides the psychological breathing room you need to focus on your recovery. If you are feeling overwhelmed by the math, using a payday loan consolidation calculator can help you visualize a realistic path toward a zero balance.
Comparing Your Options: New Loans vs. Debt Management Plans
Finding the right strategy to consolidate payday loans into one monthly payment depends heavily on your current financial health. There isn’t a one size fits all solution. While some borrowers can qualify for traditional refinancing, others need a more structured intervention to stop the bleeding. Choosing the wrong path can lead to more debt, so it’s critical to weigh options for getting out of payday loan debt with a clear understanding of your credit standing and monthly cash flow.
The primary difference lies in how the debt is handled. A new loan replaces old debt with a new creditor. A management plan restructures the debt you already have. Both aim for the same goal of simplification, but the requirements for entry are vastly different. If you have the credit score to qualify, a loan is often faster. If your credit is already damaged, a relief program provides the necessary protection to recover without further borrowing.
When a Personal Loan Makes Sense
If your credit score remains above 600, a personal loan might be your most direct exit. As of late August 2026, the average interest rate for a 36-month personal loan is 13.67%, which is a fraction of the 400% APR typical of payday lenders. Borrowers with a credit score of at least 670 may see even better terms. The primary advantage is the immediate payoff of high-interest lenders, which stops the rollover cycle instantly. For those also struggling with high revolving balances, a strategy for credit card and payday loan consolidation can simplify your entire financial life into a single, predictable date.
When a Relief Program is the Only Choice
For many, the debt trap has already damaged their credit score beyond the point of bank approval. If you have multiple defaults, a high debt-to-income ratio, or a score below 550, a relief-based management program is often the only viable path. These programs don’t rely on your credit score because they aren’t lending you new money. Instead, they focus on aggressive negotiation to stop interest and eliminate fees. This is a powerful, safer alternative to bankruptcy, allowing you to settle your obligations without the long-term legal fallout of a court filing. While it requires the discipline to stick to a new budget, it provides a definitive end date for your debt and stops the constant drain on your bank account.
5 Steps to Consolidate Payday Loans into One Monthly Payment
Taking the first step toward debt freedom requires a clear map of where you currently stand. Start by creating a comprehensive inventory of your debt. List every lender, the current balance, and the exact due dates for each obligation. This transparency is essential. Without a full view of the damage, you can’t effectively consolidate payday loans into one monthly payment. Once the numbers are on paper, you can begin the process of reclaiming your bank account from predatory lenders.
After your inventory is complete, consult with a specialist to evaluate your total debt load. They’ll help you determine if a management program is your best path forward. From there, you can enroll in a structured program that fits your monthly budget. The final, most vital step is to commit to the plan and stop taking new “advance” loans. Breaking the cycle requires a clean break from the lenders who created the trap in the first place.
Stopping the Bleeding: Revoking ACH Authorization
You have a legal right to stop automatic withdrawals from your bank account. This is a critical first step in payday loan relief. To regain control, you must notify both your bank and the lender in writing at least three business days before a scheduled transfer. A simple template is often enough: “I am revoking my authorization for [Lender Name] to withdraw funds from my account ending in [Last 4 Digits], effective immediately.” This action prevents lenders from draining your paycheck before you can even pay for basic necessities like rent or groceries.
Using a Calculator to Set Your Budget
Visualizing the finish line changes your psychological approach to debt. We encourage you to use a payday loan consolidation calculator to see how your payments will change under a structured plan. Seeing a realistic end date provides immediate psychological relief. A clear repayment date is the first step toward financial agency. When you know exactly when you’ll be debt-free, the urge to re-borrow diminishes. If you’re ready to see your new monthly payment, calculate your savings today and take the first step toward peace of mind.
Life After Consolidation: Breaking the Cycle for Good
The moment you decide to consolidate payday loans into one monthly payment, the immediate pressure of multiple lenders begins to lift. However, the true victory lies in what happens next. Sustaining your financial health requires more than just a lower interest rate; it requires a new approach to how you handle your income. Once your bank account is no longer subject to unpredictable withdrawals, you gain the ability to manage your cash flow with precision. This predictability is the foundation of long-term stability.
One of the most important steps you can take is building a “starter” emergency fund. Even a small cushion of $500 can prevent a minor car repair or medical bill from turning into a reason to return to a lender. The temptation to re-borrow is often strongest when you first start feeling relief. It’s easy to think that one small “advance” won’t hurt, but that is how the cycle restarts. When you consolidate payday loans into one monthly payment, you aren’t just paying down debt; you’re proving to yourself and future creditors that you can maintain a consistent, on-time schedule. This consistency is what eventually allows your credit score to recover from the damage of previous defaults.
Transitioning to Traditional Banking
Breaking the cycle often means changing where you keep your money. Many predatory lenders thrive on “check cashing” apps and prepaid cards that lack the consumer protections of a standard checking account. Transitioning to a traditional bank or a local credit union is a major milestone in your recovery. As you move forward, remain vigilant for “predatory” signs in future offers, such as vague APR disclosures or terms shorter than 30 days. If you find yourself struggling during this transition, the Payday Loan Hardship Program offers ongoing support and resources to keep you on the right path.
The Path to Financial Peace
The ultimate goal of this process isn’t just a zero balance; it’s the psychological peace that comes from knowing you’re in control. Regaining your agency means your paycheck belongs to you and your family, not a collection agency. Consolidation is the bridge that carries you from financial turbulence to a future of your own making. It’s a journey that requires patience, but the tangible benefit of sleeping through the night without worrying about bank alerts is worth the effort. If you’re ready to leave the debt trap behind, reach out for a confidential debt review today. Our advocates are ready to help you build the stable life you deserve.
Take Control of Your Financial Future Today
You don’t have to live in a state of constant financial turbulence. Breaking the cycle of 400% APR interest starts with a single decision to reclaim your agency and protect your income. By choosing to consolidate payday loans into one monthly payment, you replace the chaos of multiple automatic withdrawals with a structured, predictable plan that fits your actual budget. This transition doesn’t just lower your immediate stress; it allows you to build a foundation for lasting stability and financial peace.
Since 2004, Solid Ground Financial has acted as a dedicated advocate for individuals trapped in predatory lending cycles. Our no-judgment debt relief experts understand the mechanics of these traps and offer tools like our specialized payday loan savings calculator to help you visualize your path out. You’ve carried the weight of high-interest debt long enough. It’s time to move toward a future where your paycheck actually belongs to you.
Get Your Free Payday Loan Consolidation Quote Today and start your journey toward recovery. You have the power to break the cycle, and we’re here to help you every step of the way.
Frequently Asked Questions
Can I consolidate payday loans if I have very bad credit?
Yes, you can qualify for a relief program even with a poor credit history. Unlike traditional bank loans that require a high score for approval, a consolidation program focuses on managing your existing debt rather than issuing new credit. This approach allows individuals with multiple defaults or a high debt to income ratio to consolidate payday loans into one monthly payment without the hurdle of a credit check. It provides a viable path for those the banks have rejected.
Will consolidating my payday loans stop the collection calls?
Yes, enrolling in a professional management program typically stops direct harassment from lenders. Once you’re represented by an advocate, they handle the negotiations and communication with your creditors. This transition provides immediate psychological relief by moving you from a defensive position to a structured repayment plan. Most lenders stop the aggressive calls once they’re formally notified that a professional management firm is handling your account, allowing you to focus on your recovery.
How do I stop payday lenders from taking money out of my bank account?
You have the legal right to revoke your ACH authorization at any time. To do this, you must provide written notice to both the lender and your bank at least three business days before a scheduled payment. This action is a critical step in regaining control of your finances. It prevents lenders from draining your account through automatic withdrawals, ensuring your paycheck stays where it belongs until your consolidation plan is active and your budget is stabilized.
Is payday loan consolidation the same as a new loan?
No, it’s a management process rather than a new financial product. While a consolidation loan involves borrowing money from one bank to pay off another, a consolidation program restructures your current debt through expert negotiation. This means you aren’t adding more debt to your plate or paying new origination fees. Instead, you’re simplifying your scattered obligations into a single, manageable stream that’s designed to fit your actual monthly budget and life requirements.
How much can I save with a payday loan consolidation program?
The savings vary based on your total debt load and the interest rates of your current lenders. By eliminating predatory rollover fees and negotiating lower interest rates, many borrowers see their total payout drop significantly. To get a precise estimate for your situation, we recommend using a specialized payday loan consolidation calculator. This tool helps you visualize the difference between paying endless fees and making one steady payment toward your principal, highlighting the tangible benefits of relief.
How long does the consolidation process typically take?
The initial setup of a consolidation program is often completed within a few business days. However, the total time required to reach a zero balance depends on your specific debt amount and your ability to stick to the repayment schedule. Most programs are designed to provide a clear, definitive end date for your debt. This structured timeline is a far more predictable alternative to the endless cycle of re-borrowing that characterizes the predatory payday loan industry today.
Will my credit score go down if I consolidate my payday loans?
There may be a temporary dip in your credit score when you first stop making payments to predatory lenders to prioritize your consolidation plan. However, the long term impact is often positive for your financial future. By replacing scattered defaults and late payments with a consistent, on time monthly payment, you demonstrate financial responsibility to future creditors. Successfully completing a management program is a significant step toward rebuilding your overall financial standing and your long term credit health.
Can I include credit card debt in my payday loan consolidation plan?
Yes, you can include unsecured credit card balances in your overall management strategy. We specialize in both payday loan relief and credit card consolidation to help you streamline all your high interest obligations at once. Merging these different types of debt into a single payment plan simplifies your financial life. It ensures that more of your money goes toward principal reduction rather than juggling multiple interest rates and due dates across various predatory platforms.