What if the traditional banking system is actually designed to keep you trapped in a cycle of minimum payments that never touch your principal balance? It’s exhausting to wake up to harassing collection calls and the crushing weight of high-interest debt that grows no matter how much you sacrifice. You likely feel like you’re running on a treadmill that’s only getting faster. We understand that finding effective credit card consolidation for low credit scores feels nearly impossible when every traditional lender turns you away because of a three-digit number on a report.
You deserve a path forward that focuses on your recovery rather than your past setbacks. This article will show you how to merge your high-interest obligations into one manageable monthly payment, even if traditional banks have already closed their doors to you. We’ll explore how to secure lower total interest costs and establish a clear, certain date for when you’ll be entirely debt-free. We’re going to break down the specific strategies available in 2026 to help you reclaim your financial agency and finally silence the collection calls for good.
Key Takeaways
- Understand how to break the “Credit Score Trap” by moving from financial chaos to a structured, manageable repayment strategy.
- Learn why specialized debt management programs are often more effective than traditional personal loans when seeking credit card consolidation for low credit scores.
- Identify the specific consolidation options available for your credit range to avoid damaging your score with unnecessary applications.
- Discover a five-step process to inventory your debt and use a calculator to determine your exact path to a zero balance.
- Explore how consolidating your debt provides immediate psychological relief and sets the stage for rebuilding your financial agency.
The Reality of Credit Card Consolidation for Low Credit Scores
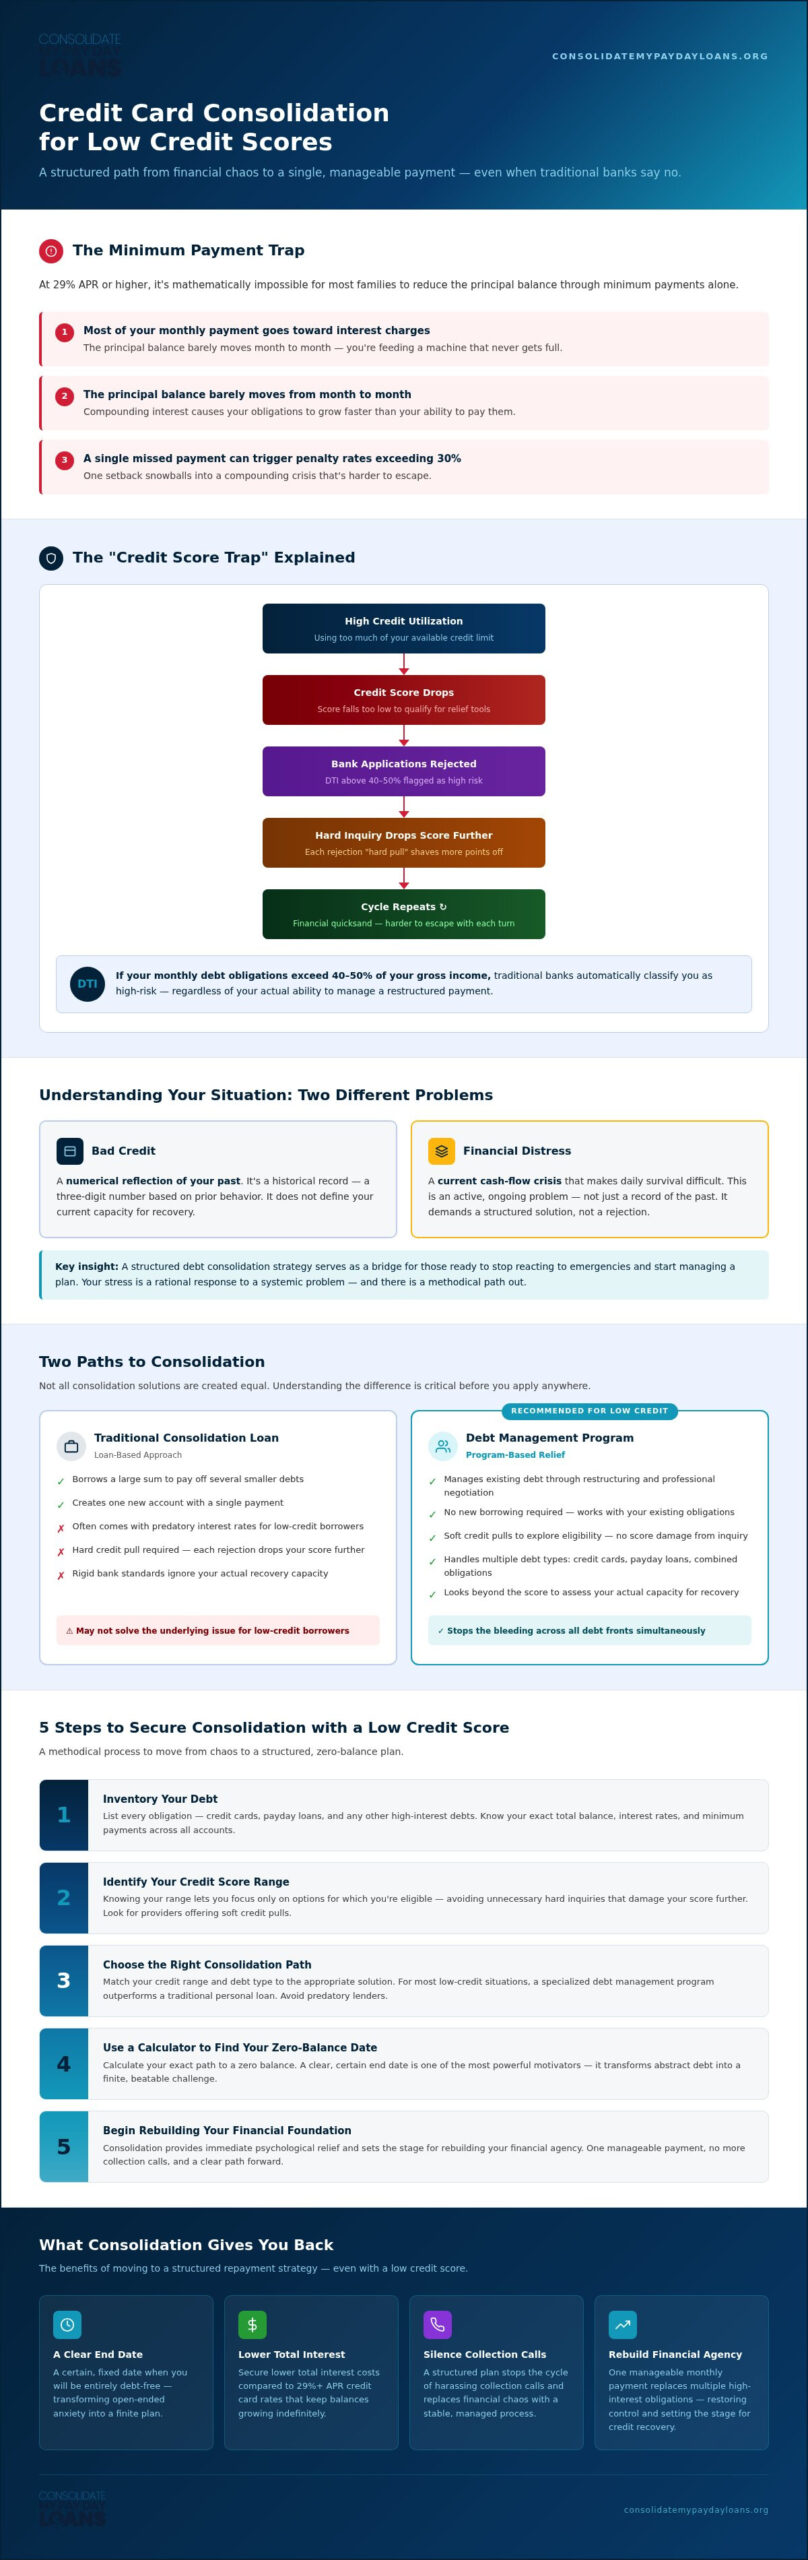
Consolidation is often misunderstood as simply taking out a new loan to pay off old ones. When you are looking for credit card consolidation for low credit scores, the definition shifts from a simple financial transaction to a total transition from chaos to structure. Many people find themselves caught in the “Credit Score Trap,” where high credit utilization-using too much of your available limit-drags your score down so low that you can’t qualify for the very tools meant to fix it. This cycle feels like being stuck in financial quicksand.
We must distinguish between having “bad credit” and being in “financial distress.” Bad credit is a numerical reflection of your past, while financial distress is a current cash-flow crisis that makes daily survival difficult. A structured debt consolidation strategy serves as a bridge for those who are ready to stop reacting to emergencies and start managing a plan. Your stress is a rational response to a systemic problem, but there is a methodical path out.
Why Traditional Banks Say No (And Why It Is Not the End)
Traditional lenders rely heavily on your debt-to-income (DTI) ratio. If your monthly debt obligations consume more than 40% to 50% of your gross income, banks view you as a high-risk gamble. They don’t see the person trying to do the right thing; they only see the data on a screen. This rigid approach often ignores your actual ability to make a single, restructured payment.
Every time you apply and get rejected, the resulting “hard pull” on your credit report can shave more points off your score. This creates a downward spiral of rejection and frustration. The key is to stop trying to “qualify” for a bank’s narrow standards and start finding a solution tailored to your actual situation. Specialized programs look beyond the score to see your capacity for recovery.
The Impact of High Interest on Your Recovery
When you’re carrying balances with 29% APR or higher, you aren’t just paying for what you bought. You’re paying a penalty for being in debt. At these rates, it’s mathematically impossible for most families to reduce the principal balance through minimum payments alone. You’re simply feeding a machine that never gets full.
The minimum payment treadmill is a trap designed by the industry to keep you paying for decades. It’s a system where:
- Most of your monthly payment goes toward interest charges.
- The principal balance barely moves from month to month.
- A single missed payment can trigger penalty rates that exceed 30%.
Compounding interest is the primary enemy of your debt recovery because it causes your obligations to grow faster than your ability to pay them.
How Consolidation Works When You Have Less-Than-Perfect Credit
Finding options for credit card consolidation for low credit scores often feels like looking for a needle in a haystack. Most people think their only choice is a new loan, but when your score is low, that door is often locked. Instead of risking more damage to your score with hard inquiries, focus on providers who offer soft credit pulls. These allow you to explore your eligibility without causing another dip in your rating. It’s a safer, more methodical way to begin your recovery journey.
Many individuals find themselves juggling multiple types of high-interest debt simultaneously. You might have a few credit cards near their limits alongside a payday loan that’s draining your checking account every two weeks. A unified strategy doesn’t treat these as separate problems. It looks at your total financial picture to create one cohesive path forward. This approach stops the bleeding across all fronts, ensuring that no single debt continues to undermine your progress.
Loan-Based Consolidation vs. Program-Based Relief
When you need credit card consolidation for low credit scores, you must understand that not all solutions are created equal. A traditional consolidation loan works by borrowing a large sum to pay off several smaller debts. This creates one new account. However, for those with less-than-perfect credit, these loans often come with predatory interest rates that don’t actually solve the underlying issue. Program-based relief is different. It manages your existing debt through restructuring and professional negotiation rather than new borrowing. This is particularly helpful for those dealing with a mix of obligations. You can find more details on how to handle these combined challenges in our guide on Credit Card and Payday Loan Consolidation: A Unified Exit Strategy for 2026. Before making a choice, it’s wise to review the official credit card debt consolidation guidance from the CFPB to understand the risks of different methods.
The Role of Specialized Advocates
When you’re overwhelmed, the last thing you want is another battle with a creditor. Specialized advocates act as a protective barrier between you and the companies you owe. They use professional negotiation to lower interest rates and waive late fees that have ballooned your balance over time. This isn’t just about the numbers; it’s about regaining your peace of mind.
These experts help stop the harassing collection calls that keep you in a state of constant anxiety. They move you from being a target of aggressive collection tactics to being a participant in a structured, predictable recovery plan. If you’re tired of fighting alone against a system designed to keep you in debt, it might be time to explore professional relief options that prioritize your financial health over lender profits.
Comparing Options: Which Consolidation Path Fits Your Score?
Your credit score is a snapshot of your past, but it doesn’t have to dictate your future. When looking for credit card consolidation for low credit scores, the right path depends heavily on where you sit on the numerical scale. Borrowers with scores between 580 and 620 often find themselves in a “middle ground” where they might qualify for high-interest personal loans. Conversely, those with scores below 580 usually find that traditional borrowing is either unavailable or prohibitively expensive. Understanding these boundaries helps you stop wasting time on applications that will only lead to more rejections.
The most common fear we hear is whether these programs will hurt your credit more than doing nothing. It’s a valid concern. However, staying trapped in a cycle of high utilization and near-missed payments is often far more damaging to your score over time. Moving toward a structured plan allows you to address the root cause of the problem. By reducing your total debt and ensuring consistent payments, you create the conditions for your score to eventually recover and thrive.
Bad Credit Personal Loans: The Pros and Cons
If your score is in the high 500s, you might be offered a “bad credit” personal loan. The primary benefit is the fixed term. You’ll know exactly when the debt will be gone. The downside is the cost. These loans often come with high APRs that can sometimes mirror the predatory tactics seen in the payday loan industry. You must be vigilant. Always check for no-prepayment penalties; you want the freedom to pay the loan off faster if your financial situation improves without being punished for your success.
Avoid lenders who focus solely on your next paycheck rather than your overall ability to repay. A legitimate loan should help you exit debt, not just shift it to a more expensive bucket. If the interest rate is so high that the monthly payment doesn’t feel manageable, a loan is likely the wrong tool for your recovery.
Debt Management and Relief Programs
For those whose scores have dipped below 580, program-based relief is often the most realistic and effective option. These programs don’t require you to take out a new loan. Instead, they focus on a single manageable payment that is distributed to your creditors through a structured plan. This is an excellent alternative for individuals who have been turned away by banks but are committed to resolving their obligations. It provides a clear methodology for improvement without the need for a high-interest balance transfer.
Before committing to any path, it’s helpful to review the official credit card debt consolidation guidance from the CFPB to ensure you understand the landscape. If you are dealing with a complex mix of credit cards and high-cost short-term loans, you may benefit from Payday Loan Relief: Comprehensive Programs to Break the Debt Cycle in 2026. These specialized programs are designed to handle the nuances of multiple debt types while providing the psychological peace of a unified exit strategy.
5 Steps to Secure Consolidation with a Low Credit Score
Securing credit card consolidation for low credit scores isn’t about luck. It’s about a methodical approach that replaces anxiety with a clear, actionable strategy. Follow these steps to move from being overwhelmed to being in control of your financial future.
- Step 1: Inventory your debt. Create a detailed list of every credit card balance, interest rate, and payday loan. You can’t fix what you haven’t measured.
- Step 2: Use a calculator. Plug your numbers into a payday loan consolidation calculator to see the real impact of restructuring. This helps you visualize the light at the end of the tunnel.
- Step 3: Audit your credit report. Check for errors like duplicate accounts or incorrect late fees that might be suppressing your score. Removing these small mistakes can provide a much-needed lift.
- Step 4: Compare specialized providers. Look for advocates who look beyond your FICO score and focus on your current ability to manage a single monthly payment.
- Step 5: Commit to the plan. Once you start, stop the cycle of new borrowing. This step is essential to ensure your new structure actually leads to total debt freedom.
Preparing Your Financial Documentation
Legitimate programs need to see your full financial picture to advocate effectively for you. You’ll need your most recent pay stubs, bank statements from the last 90 days, and current statements for every debt you want to include. Showing stable income is often more important than the score itself. It proves you have the capacity to succeed in a structured management plan. You should stop using all credit cards at least 30 days before applying to ensure your balances are stable and your commitment is clear.
Evaluating Legitimate Consolidation Companies
The debt relief industry has its share of pitfalls. Watch for red flags like upfront fees for loans or “guaranteed” approvals that sound too good to be true. A trustworthy partner will offer a payday loan hardship program to support you through the toughest parts of the process. Always check for a long history of consumer advocacy; companies like Solid Ground Financial have been operating since 2004. If you’re ready to take the first step toward a debt-free life, explore our consolidation options to see how we can help you regain your financial agency.
Beyond the Payment: Rebuilding Your Financial Foundation
Reaching the end of the consolidation process is more than a financial milestone. It’s a psychological transformation. For years, you’ve likely felt like a victim of a system designed to keep you in debt. By choosing credit card consolidation for low credit scores, you’re making a conscious decision to step into the role of a manager. This shift in agency is the true foundation of long-term financial health. You’re no longer just reacting to collection calls; you’re executing a methodical plan that has a clear end date.
Consolidation provides a structured exit strategy that avoids the long-term devastation of bankruptcy. While bankruptcy might seem like a quick fix, it can haunt your financial record for up to a decade. A management plan allows you to resolve your obligations with dignity while actively rebuilding your standing in the financial world. We position ourselves as your partner in this recovery, providing the stable anchor you need to weather the storm and reach calmer waters. This process is about regaining personal agency over your financial life, one step at a time.
The Path to Credit Score Recovery
Your credit score is calculated using several key factors, with two of the most significant being payment history (35%) and credit utilization (30%). When you consolidate, you’re addressing both. By moving high-interest balances into a structured plan, your utilization ratio naturally drops, which can lead to visible score improvements within a few months of consistent activity. It’s a steady progression rather than an overnight miracle. For those weighing their options, it’s worth exploring Payday Loan Consolidation Instead of Bankruptcy: A Strategic Exit Plan for 2026 to understand why this path preserves your future options.
Protecting Your Future Agency
Once the immediate fire of high-interest debt is extinguished, your focus must shift to protection. The goal is to ensure you never find yourself back in the cycle of predatory lending. This starts with building a modest emergency fund. Even a small buffer can prevent the need for a new credit card or a high-cost loan when an unexpected car repair or medical bill arrives. It’s about creating a safety net that allows you to maintain your newfound agency and stay on the path toward total freedom.
Regaining your peace of mind is the ultimate goal of any structured plan. We’re committed to leading you toward a safer alternative to the high-cost traps that have held you back. If you’re ready to stop the cycle and start your recovery, we’re here to provide the expertise and advocacy you deserve. Using credit card consolidation for low credit scores is a powerful way to reclaim your future. Your journey to financial stability starts with a single, manageable step forward.
Take Your First Step Toward Lasting Financial Freedom
Reclaiming your financial life starts with a shift from feeling like a victim of high-interest debt to becoming the manager of a structured plan. We’ve explored how credit card consolidation for low credit scores serves as a bridge, moving you away from the crushing weight of high APRs and toward a single, manageable monthly payment. By choosing a strategic exit plan instead of bankruptcy, you protect your future agency and begin the methodical process of rebuilding your credit score through lowered utilization and consistent progress.
You don’t have to navigate this turbulence alone. Since 2004, our team has provided expert negotiation and specialized programs designed specifically for those with less-than-perfect credit. Whether you are struggling with revolving balances or need unified relief for both credit cards and payday loans, a clear path forward exists. It’s time to silence the collection calls and regain your psychological peace with a partner who understands the systemic traps of the lending industry. Get your free debt consolidation estimate today and discover how a structured methodology can lead you back to solid ground. Your recovery is possible, and it begins today.
Frequently Asked Questions
Can I consolidate credit card debt with a 500 credit score?
Yes, you certainly can. While traditional banks will likely reject a 500 score, specialized debt management and relief programs don’t rely solely on FICO numbers. These programs focus on your income and your current ability to handle a single monthly payment. They restructure your existing debt rather than issuing a new loan. This makes credit card consolidation for low credit scores possible for those who have been turned away by mainstream lenders.
Will credit card consolidation hurt my credit score?
The impact depends on the method, but the long-term result is usually positive. If you use a relief program, you might see a temporary dip as your accounts are restructured. However, as your total debt utilization drops and you establish a consistent history of on-time payments, your score typically begins to recover. Consolidating is almost always better for your score than continuing a cycle of high utilization and missed payments.
How much can I save by consolidating my credit cards?
Savings vary based on your current interest rates and total balance. Many high-interest cards carry APRs near 30%, which makes paying down the principal nearly impossible. By negotiating lower rates or merging debts into a structured plan, you can save thousands of dollars in interest costs over the life of the debt. You can use our specialized calculator to get a clearer picture of how much your specific monthly payment could be reduced.
What is the difference between debt consolidation and debt settlement?
Consolidation focuses on merging multiple debts into one manageable plan, often by lowering interest rates while paying the full principal balance. Settlement involves negotiating with creditors to accept a lump sum that is less than the total amount you owe. While settlement can reduce the total balance, it often has a more significant negative impact on your credit report. Consolidation is generally viewed as a more structured and less damaging path to financial recovery.
Can I consolidate both payday loans and credit cards together?
Yes, you can combine these different types of unsecured debt into a single relief plan. Many people find themselves trapped in a cycle involving both high-interest credit cards and predatory payday loans. Our specialized programs are designed to handle these complex debt portfolios simultaneously. This unified approach stops the aggressive collection tactics from multiple sources and creates one predictable path toward becoming completely debt-free and reclaiming your financial agency.
How do I know if a consolidation company is legitimate?
Look for a long history of consumer advocacy and transparent business practices. Legitimate companies don’t charge upfront fees for consolidation loans and are open about their fee structures. Check for established parent companies; for example, we operate under Solid Ground Financial, which was founded circa 2004. A trustworthy partner will prioritize your financial health and offer resources like hardship programs rather than just pushing for a quick, high-cost loan product.
What happens if I am rejected for a consolidation loan?
Rejection for a loan is not the end of your options. If a bank says no because of your debt-to-income ratio or score, you can still qualify for program-based credit card consolidation for low credit scores. These relief programs don’t require a new loan approval. Instead, they focus on restructuring your existing obligations into a payment you can actually afford. This ensures you still have a methodical path out of debt regardless of your score.
How long does the consolidation process usually take?
The initial setup of a consolidation plan can often be completed within a few days. However, the journey to becoming entirely debt-free typically takes between 24 and 48 months, depending on your total balance and budget. The process begins with a thorough inventory of your debts and a soft credit pull. Once the plan is active, you’ll have a clear, certain date for when your financial recovery will be complete and your debt will be gone.