Every day you wait to address high-interest debt, you’re essentially handing over a massive portion of your paycheck to a lender who has no intention of seeing you succeed. You likely feel the constant drain of recurring ACH withdrawals and the crushing anxiety of wondering if your bank account will be empty before you can even pay your rent. It feels like you’re running on a treadmill that’s only getting faster while your actual debt balance remains stubbornly frozen.
Understanding the compounding risks of not consolidating payday loans is the first step toward breaking free from a cycle that currently averages a staggering 391% APR in 2026. You deserve to stop the endless loop of fees and protect your hard-earned money from unauthorized hits. This guide will help you identify the hidden financial, legal, and psychological dangers of delaying your exit strategy and show you how to regain your personal agency. We’ll explore the mechanics of predatory fees, the reality of aggressive collection tactics, and the clear, single-payment path to reaching zero debt once and for all.
Key Takeaways
- Identify how the “rollover trap” and 391% APR interest rates turn small debts into long-term financial liabilities that never seem to decrease.
- Recognize the legal transition from simple collection calls to aggressive debt buyers and the serious threat of civil judgments or wage garnishment.
- Understand how “financial fog” and chronic debt stress can impair your daily decision-making and damage your personal relationships.
- Evaluate the compounding risks of not consolidating payday loans, including the very real possibility of losing access to your primary bank account.
- Learn how a professional relief program uses insider knowledge to negotiate with lenders and stop the cycle of predatory fees.
The Financial Bleed: Immediate Risks of the Payday Loan Cycle
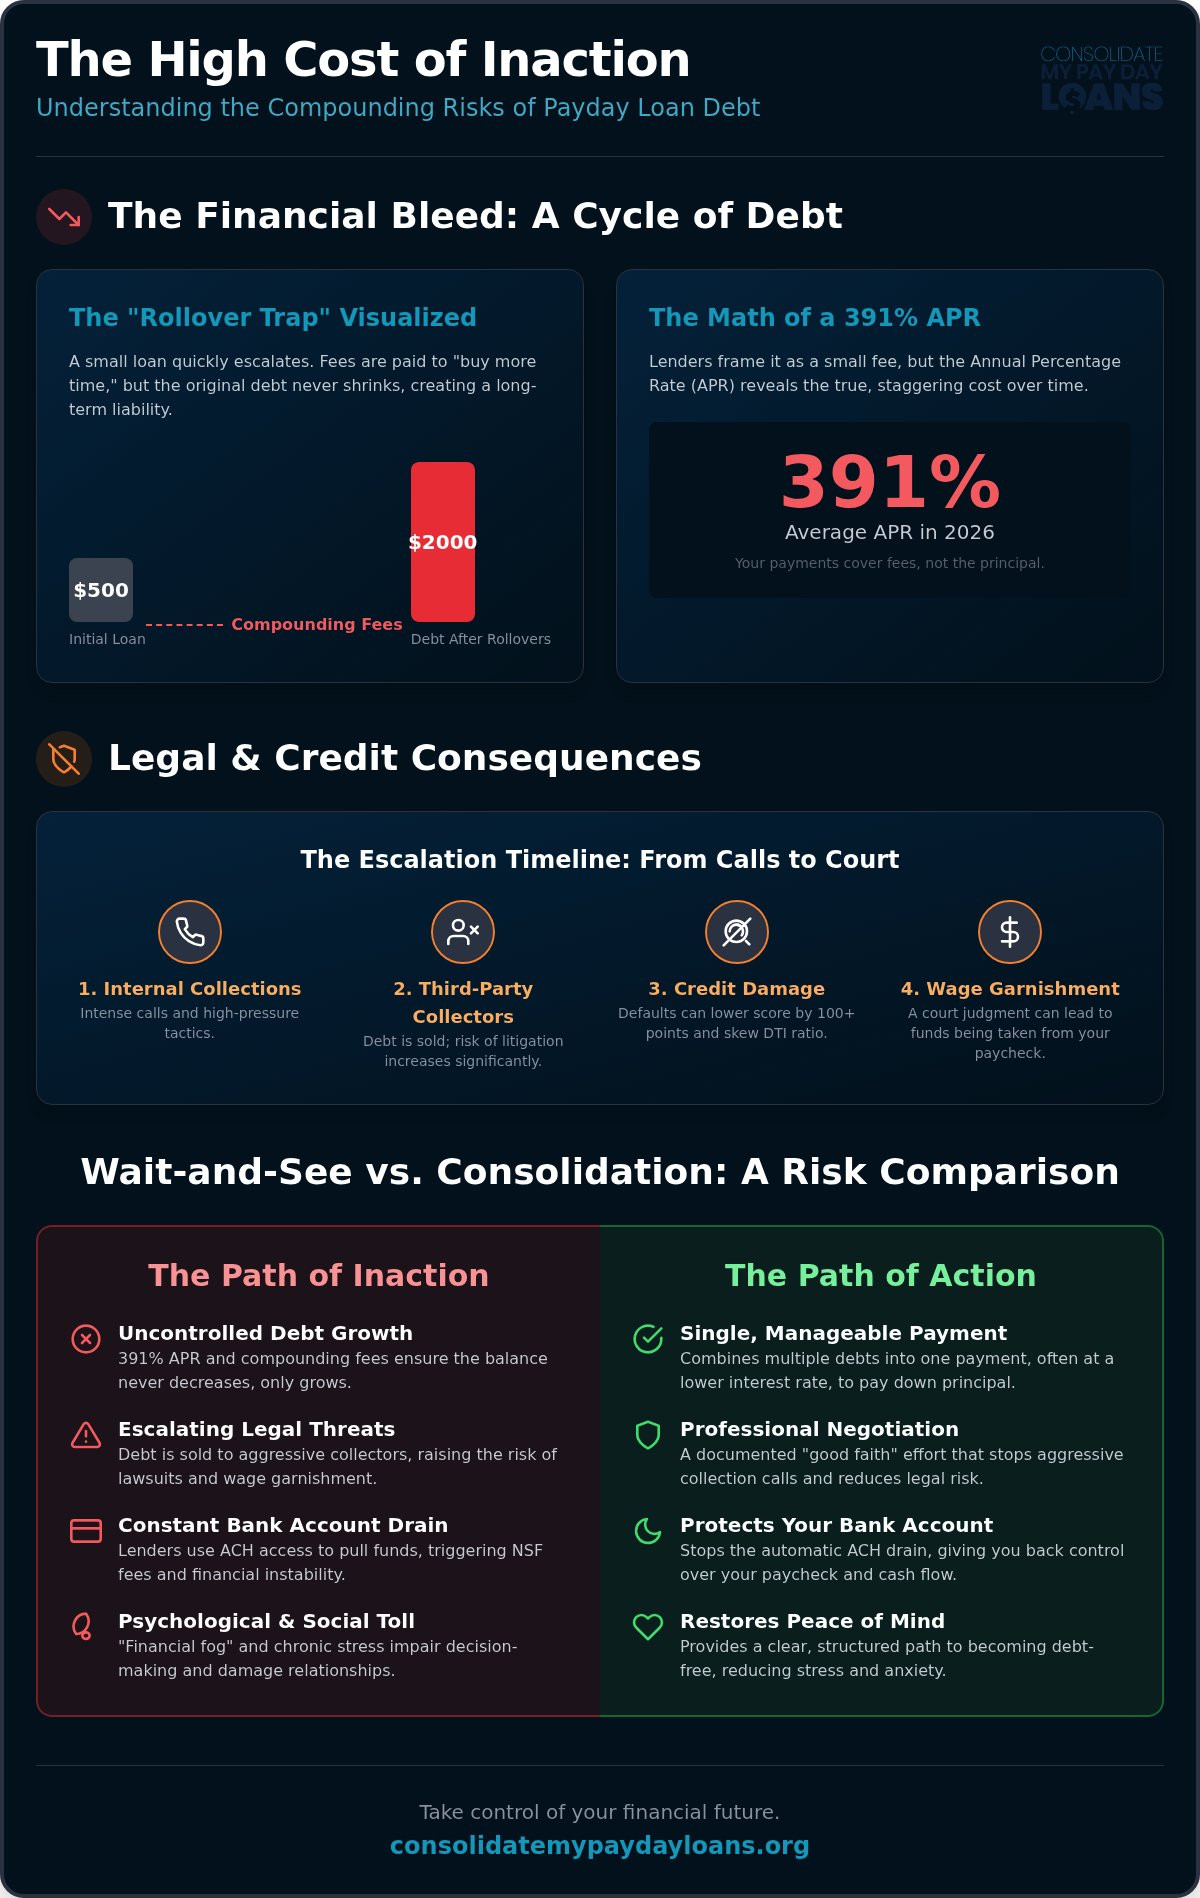
The financial bleed starts quietly but accelerates with terrifying speed. When you’re trapped in the Payday loan cycle, your payments often do nothing to lower the amount you actually owe. One of the primary risks of not consolidating payday loans is that you’re essentially paying a “stay in debt” fee every two weeks rather than making progress toward freedom. If you ignore a $500 loan and simply roll it over, the compounding fees can easily transform that modest debt into a $2,000 liability within just a few months. This isn’t just bad luck; it’s the systemic design of high-interest lending.
Waiting even one more month to act has a literal price tag. Every rollover fee you pay is money that could have gone toward your rent, groceries, or car payment. This “cost of inaction” creates a scenario where the lender prioritizes their profit over your survival. By delaying a resolution, you aren’t just pausing your progress. You’re actively increasing the total amount you will eventually have to pay back.
The Math of a 400% APR Rollover
Lenders often frame their costs as a simple $15 fee for every $100 borrowed. While that sounds manageable, it translates to a staggering 391% APR in 2026. When you pay for a rollover, you aren’t paying down the principal balance. You’re simply buying two more weeks of time. The debt trap is a cycle where fees exceed the original loan amount. Over six months, these fees can triple the original balance without a single cent going toward the actual debt. This math is designed to keep you paying indefinitely while the principal remains untouched.
Stopping the Automatic Bank Account Drain
Lenders use ACH access to drain your bank account the moment your paycheck hits. If the funds aren’t there, they may attempt to withdraw multiple smaller amounts. This often triggers several Non-Sufficient Funds (NSF) fees from your bank, further depleting your resources. Learning how to stop payday loan automatic withdrawals is a critical first step in relief. Consolidation provides a protective shield for your primary checking account. It allows you to regain control over your cash flow and ensures that your essential living expenses come before a lender’s aggressive collection attempts.
Legal and Credit Consequences: What Happens When You Wait?
Many people believe that if they stop answering the phone, their payday debt will simply fade away. This is a dangerous misconception. When you delay action, lenders don’t just give up. They often sell your debt to aggressive third-party buyers who specialize in litigation. One of the most significant risks of not consolidating payday loans is the eventual shift from annoying phone calls to a formal court summons. Unlike the original lender, these debt buyers are highly motivated to secure civil judgments. These judgments can lead to wage garnishment or bank account levies that bypass your permission entirely.
According to the CFPB, understanding the risks of the payday loan cycle is essential for protecting your financial future. If you ghost a lender, you lose your leverage. Consolidation acts as a documented “good faith” effort. It shows that you’re taking professional steps to resolve the debt, which can be a powerful defense if legal issues arise.
From Collection Calls to Court Summons
The escalation timeline is predictable. For the first 30 to 60 days, you’ll likely deal with internal collections. They might use intense scare tactics. Some even claim you’ve committed “check fraud” to pressure you into paying. These are usually empty threats, but they’re incredibly stressful. If you don’t have a consolidation plan in place, the account eventually moves to third-party collectors. At this stage, the risk of a lawsuit becomes much higher. Entering a managed program replaces these hostile interactions with a structured, professional resolution.
Long-term Damage to Your Debt-to-Income (DTI) Ratio
Payday loans are often called “invisible debt” because they rarely appear on your credit report while you’re current. However, they become very visible the moment they default. A single default can tank your score by 100 points or more. Beyond the score itself, these loans create a heavy “Credit Anchor” by skewing your debt-to-income (DTI) ratio. Mortgage and auto lenders look at your monthly obligations. Multiple high-interest payments make you look like a high-risk borrower.
Choosing to consolidate your payday debt transforms your status from a struggling debtor to a managed client. This shift doesn’t just lower your stress. It begins the process of cleaning up your financial profile so you can qualify for better opportunities in the future. Ignoring the risks of not consolidating payday loans only deepens the hole. Taking action today ensures you aren’t held back by the mistakes of the past.
The Psychological and Social Toll of Unmanaged Debt
Debt isn’t just a number on a screen. It’s a weight that follows you into every room. Chronic stress from high-interest debt creates a “Financial Fog” that makes even simple decisions feel impossible. When you’re constantly calculating how to cover the next rollover, your brain stays in survival mode. This constant state of alert prevents you from thinking strategically about your future. One of the often-overlooked risks of not consolidating payday loans is this mental exhaustion. It drains your energy and makes it harder to perform at work or show up for your family.
The CFPB highlights the risks of the payday loan cycle as a trap that often leads to long-term financial distress. This distress doesn’t stay contained in your bank account. It leaks into your home life. Many people hide their debt from partners or family members out of shame. This financial secrecy builds a wall between you and your loved ones. It creates a hidden cost of isolation that no balance sheet can truly capture.
Breaking the “Debt Shame” Silence
Professional consolidation services aren’t here to judge your past choices. They exist to provide a stable anchor while you navigate the storm. A structured plan significantly reduces the “cognitive load” of managing five or six different lenders with different due dates and withdrawal patterns. Regaining agency over your financial life is the first step toward restoring your personal dignity. You stop being a target for collectors and start being a person with a clear, manageable path forward.
Preventing the Social Fallout of Collections
Aggressive lenders don’t always respect personal boundaries. They may try to contact your workplace or the personal references you provided on your initial application. This social fallout can jeopardize your employment and damage your reputation among peers. Consolidation programs act as a vital buffer between you and these predatory entities. Ignoring the psychological risks of not consolidating payday loans can be just as damaging as the interest rates themselves. You gain immediate peace of mind knowing that you have a single, predictable monthly payment. This transition allows you to move from a state of constant panic to a focused, strategic path toward zero debt.
Wait-and-See vs. Consolidation: A Risk Comparison
Choosing to wait is a financial gamble where the house always wins. Many borrowers believe that “one more month” of rollovers will give them the breathing room they need to catch up. In reality, the risks of not consolidating payday loans are mathematical certainties. If you carry a $1,000 balance at the 2026 average of 391% APR, you’ll pay roughly $150 in fees every two weeks. Over six months, those rollovers cost you $1,800 in fees alone, yet you still owe the original $1,000. By contrast, a structured consolidation plan focuses on principal reduction. This allows you to exit the debt for a fraction of that total cost.
A single payment payday loan consolidation isn’t just a convenience. It’s a strategy to stop the bleeding. While waiting feels like a neutral choice, it’s actually an active decision to continue losing money to predatory interest rates.
The Danger of the “Double-Up” Strategy
Desperation often leads to the “Double-Up” strategy. This happens when you borrow from “Lender B” just to cover the interest or principal due to “Lender A.” It’s a fatal error for your financial health. This pattern is technically known as the “Debt Spiral.” It accelerates your risk of default because you’re now managing two high-interest obligations instead of one. Consolidation halts this spiral by freezing new interest and combining your balances into one manageable path. It replaces chaotic borrowing with a disciplined, professional resolution.
Preserving Your Banking Relationship
One of the most severe risks of not consolidating payday loans is the permanent loss of your banking access. When lenders repeatedly hit your account for funds that aren’t there, they trigger multiple Non-Sufficient Funds (NSF) fees. If your account remains negative for too long, the bank will close it and report you to ChexSystems. This is a specialized database that banks use to screen new customers. Being blacklisted by ChexSystems makes you “unbanked.” This status complicates your entire life, making it nearly impossible to receive direct deposits or pay bills online.
You can use a payday loan consolidation calculator to visualize these risks in real dollars. Seeing the total cost of rollovers versus a managed plan provides the clarity needed to act. Don’t wait until your bank account is closed and your options are gone. You can secure your financial exit strategy and protect your banking future by choosing a professional relief program today.
Take Control with a Professional Payday Loan Relief Program
Choosing a professional path means you no longer have to face aggressive lenders on your own. Consolidate My Payday Loans (Solid Ground Financial) specializes in stepping between you and the companies draining your bank account. While many individuals try to negotiate with lenders themselves, the risks of not consolidating payday loans through a professional program often include being ignored or pushed into even worse terms. Lenders are significantly more likely to provide concessions to established advocates who understand their internal collection policies and legal limitations.
Your first 24 hours in a relief program provide an immediate sense of relief. We begin the process of notifying your lenders that you are now represented by a professional mediation service. This simple step often stops the constant barrage of collection calls and emails that fuel your daily anxiety. Instead of managing five or six different due dates, you move toward a single, predictable monthly payment that actually reduces your principal balance. This structured approach ensures that your money works for you, not for the lender’s bottom line.
The Power of Professional Negotiation
Our team uses insider knowledge gained over decades to challenge the predatory nature of high-interest debt. We know exactly which fees can be waived and which interest rates can be lowered to make your debt manageable. The payday loan relief program is designed to stop lender harassment and provide you with a dedicated advocate who understands the systemic traps of the industry. This level of mediation is far more effective than DIY attempts because it leverages professional trust and proven strategies to secure a better outcome for your specific situation.
Your Path to Financial Peace in 2026
The ultimate goal of this journey is to restore your personal agency and psychological peace. By the end of the program, you’ll see a significant improvement in your debt-to-income ratio and a dramatic reduction in daily stress. You don’t have to live in fear of the next ACH withdrawal or the next aggressive collection call. Taking the first step is simple and provides the clarity you need to move forward with confidence. You can begin protecting your financial future and your bank account right now.
Get your free payday loan consolidation estimate here. and discover how quickly you can move from survival mode to a clear, single-payment path toward zero debt. The risks of not consolidating payday loans are too high to ignore for another day. Let us help you secure your exit strategy and regain control over your financial life.
Secure Your Path to Financial Peace
The compounding risks of not consolidating payday loans extend far beyond your bank balance. Every day you remain in the rollover cycle, you face a systemic trap designed to keep you in debt permanently. We’ve explored how delaying action leads to aggressive legal escalation, the potential loss of your banking access, and a heavy psychological toll that affects every part of your life. You don’t have to navigate these predatory lending practices alone. There is a structured, professional way to stop the bleed and protect your future.
Solid Ground Financial brings over 20 years of experience in debt management to your corner. As a dedicated advocate for victims of predatory lending, we offer transparent, no-obligation savings estimates to help you visualize your exit strategy. You deserve a clear, single-payment path that actually reduces your balance and restores your personal agency. Start your journey to financial freedom with a free payday loan consolidation consultation. You’ve carried this burden long enough; it’s time to breathe again and look toward a debt-free future with confidence.
Frequently Asked Questions
What happens if I just stop paying my payday loans?
Simply stopping payments triggers a cascade of negative events. Lenders will immediately escalate collection calls and make frequent attempts to withdraw funds from your bank account via ACH. These attempts often result in multiple Non-Sufficient Funds (NSF) fees from your bank, further draining your resources. One of the primary risks of not consolidating payday loans is that the debt won’t disappear; it will likely be sold to aggressive third-party agencies that specialize in litigation.
Can a payday lender sue me if I do not consolidate?
Yes, payday lenders or the debt buyers who purchase your account can pursue legal action against you. If they secure a civil judgment in court, they may be granted the right to garnish your wages or levy your bank accounts. Consolidation provides a structured, professional alternative that demonstrates a documented “good faith” effort to repay. This mediation often stops the legal escalation before it reaches the courtroom, protecting your income and personal assets.
Will consolidating my payday loans hurt my credit score?
The impact on your credit score depends on the specific method used. While some relief programs may cause a temporary dip as accounts are settled, this is often far less damaging than a default or a public civil judgment. Over time, consolidating multiple high-interest payments into a single, manageable plan improves your debt-to-income (DTI) ratio. This shift helps rebuild your financial profile, making you a more attractive candidate for traditional car or home loans in the future.
How long does the payday loan consolidation process take?
You can begin the relief process almost immediately. After your initial consultation, the first 24 hours are critical for notifying lenders of your representation and stopping aggressive collection calls. The total duration of the program varies depending on the amount of debt you carry and the monthly payment amount you can comfortably afford. Most clients see a significant reduction in their financial stress within the first few weeks of entering the program.
Can I consolidate both payday loans and credit card debt at the same time?
Yes, you can combine these different types of unsecured debt into a single management plan. Consolidate My Payday Loans provides specialized services for both payday loan relief and credit card consolidation. Streamlining your obligations into one monthly payment simplifies your financial life and ensures that all your high-interest debt is being negotiated simultaneously. This comprehensive approach is often the most efficient way to lower your total monthly out-of-pocket costs and reach zero debt.
What is the difference between a consolidation loan and a relief program?
A consolidation loan is a new line of credit used to pay off existing lenders, which requires a decent credit score to qualify. In contrast, a payday loan relief program focuses on professional negotiation and management of your current debts. Relief programs are designed for individuals who may not qualify for traditional bank loans. These programs use “insider knowledge” to lower interest rates and waive predatory fees without requiring you to take on additional debt.
How much can I actually save by consolidating my payday loans?
Savings vary based on your total debt amount and the specific lenders involved. By negotiating to lower interest rates from 391% APR down to manageable levels and waiving late fees, many clients significantly reduce their total repayment amount. To get a specific estimate tailored to your situation, you can use a specialized payday loan consolidation calculator. This tool helps you visualize the literal price of inaction versus the benefits of a professional relief strategy.
Can I still get a bank account if I have unpaid payday loans?
It becomes increasingly difficult to open new bank accounts if your current one is closed due to unpaid payday loans. Banks often report negative account balances and excessive NSF fees to ChexSystems, a database used to screen new customers. One of the long-term risks of not consolidating payday loans is being labeled “unbanked,” which prevents you from receiving direct deposits or paying bills online. Consolidating your debt helps protect your current banking relationship and preserves your future access.